The morning after I turned eighteen, my younger brother thanked me for buying him a house I had never agreed to pay for, and my father’s signature on the purchase agreement made me question everything my family had been telling me…
The morning after I turned eighteen, my younger brother thanked me for buying him a house I had never agreed to pay for, and my father’s signature on the purchase agreement made me question everything my family had been telling me…
In our house in Greenville, South Carolina, my father made the decisions and my mother explained why the rest of us should accept them. Pierce and Harriet Whitlock called it keeping the family together. I grew up thinking that asking where money came from was somehow more offensive than spending it without asking.
My father helped run the family business, and he was proud of being the person everyone called when something needed approving. If my younger brother Nolan asked how an order was filled or why a payment had been delayed, Dad took time to explain. When I asked the same questions, he told me to concentrate on school.
My older sister, Fallon, usually backed him up. She’d say I always needed my own way. Nolan wasn’t responsible for the difference in how we were treated, but I watched him walk into offices I was told were no place for a girl my age.
The person who opened those doors for me was my grandfather, Virgil Whitlock. He didn’t give me a fancy title or tell me that being his granddaughter made me important. He put a report on the desk between us and asked, “What do you think these numbers are saying?”
At first, I stumbled over the difference between money coming in and money the company actually kept. Grandpa let me work it out. When I couldn’t explain a figure, he showed me which invoice, receipt, or payment record I needed to examine instead of providing an answer I could memorize.
One afternoon, he handed me a stack of supplier invoices and asked me to compare them with payments already made. I found a delivery charge entered twice, checked it a second time, and brought him both records. He had the mistake corrected, then asked me to explain how I’d caught it.
After that, I helped organize contracts, match customer receipts to deposits, and prepare expense summaries for his review. I learned that an unexplained increase didn’t automatically mean somebody was cheating. Sometimes a supplier had simply raised its rates, and sometimes you had to keep looking until the supporting paperwork made sense.
My grandmother, Lillian, saw us bent over those papers whenever she came by with lunch. She once told me that Grandpa valued the fact that I could explain my reasoning, even when my answer wasn’t right the first time. Nobody at home had described my questions as useful.
As I got older, Grandpa let me take on work that mattered. I reviewed costs at a warehouse that held too little inventory to justify its rent, utilities, and transportation expenses. After the operations manager checked my estimates, Grandpa approved moving those supplies into a larger facility the company already owned.
I also helped the finance manager compare expected customer payments with payroll, supplier bills, and scheduled debt payments. When two large customers looked likely to pay late, I suggested postponing equipment we didn’t urgently need. We checked the dates with the sales team, adjusted the schedule, and avoided borrowing just to cover a temporary gap.
Grandpa made me explain that recommendation to people who had worked at the company longer than I’d been alive. My hands wrinkled my notes. But he didn’t rescue me when someone questioned a number; he waited for me to open the report and show my work.
When his health began to fail, my visits weren’t always about business. I helped arrange appointments, picked up prescribed medication, and sat with him on days when he didn’t feel like discussing accounts. I never asked him what he planned to leave me, because I wanted him to know my help didn’t come with a price tag.
One afternoon, while we were reviewing an annual budget, he asked why I kept showing up when my parents didn’t seem to care about my work. I told him the business had supported our family for years, and I didn’t want its future decided by people who never bothered to understand it. He looked at me for a long moment and said I had learned because I cared about keeping it alive.
Later, Grandpa asked me to meet with his estate attorney, Marshall Reed. Marshall explained a trust that would hold Grandpa’s designated assets, including ownership interests in the company, and named me as its sole beneficiary. The assets were worth about three million dollars, but the documents made a clear distinction between owning an interest and having immediate permission to spend company money.
Grandpa reviewed the terms himself. Marshall explained who would administer the trust before I reached the required age, which records needed to be kept, and how control would pass under the documents. No one said my parents could divide the assets because they thought that would be fair to the other children.
Grandpa died before my eighteenth birthday. I missed the ordinary sound of him asking what I thought about a report, and I kept the copies of the trust papers Marshall gave me in a folder I could open whenever I needed to understand something. I knew being named a beneficiary wasn’t the same as having authority to bypass the company’s rules.
After the funeral, Dad told the managers that he and Mom would oversee staffing, purchasing, and financial administration while I finished school. He called it temporary support, but nobody offered me an end date or explained how decisions would be checked. I watched more carefully because the business still had employees and bills, regardless of who sat at the head of our dinner table.
Dad soon put Nolan in accounting, handling cash records, supplier accounts, and payment requests. He even gave him responsibility for the company safe and daily reconciliations. When I asked what training Nolan had received and who checked the payments he prepared, Mom said he needed experience and Dad accused me of making a family arrangement difficult.
The old procedure required one person to prepare a payment and another authorized person to approve it. Dad started allowing exceptions, and Mom told employees that urgent invoices could be supported with paperwork later. It sounded convenient until unfamiliar vendor names and repeated service charges started appearing in the reports I was still permitted to see.
I asked for contracts and evidence that the work had been done. One invoice described maintenance without a matching service request; another claimed a delivery that nobody in receiving could confirm. Dad said the files were being reorganized, so I wrote down the references rather than accusing anyone before I knew what the records could prove.
Around the same time, Nolan began showing Fallon a house listing and talking about a deposit. He said his salary and help from our parents would cover it, though his earnings didn’t seem to match the amount he was discussing. I had no right to inspect his private accounts, and I didn’t pretend that a house purchase alone proved anything.
The next cash report showed less money available than our forecast predicted, even though sales were steady and major customers had paid. I requested the breakdown of the new vendor payments and the names of the people who authorized them. Dad promised an explanation after the monthly books closed, but the documents still hadn’t arrived.
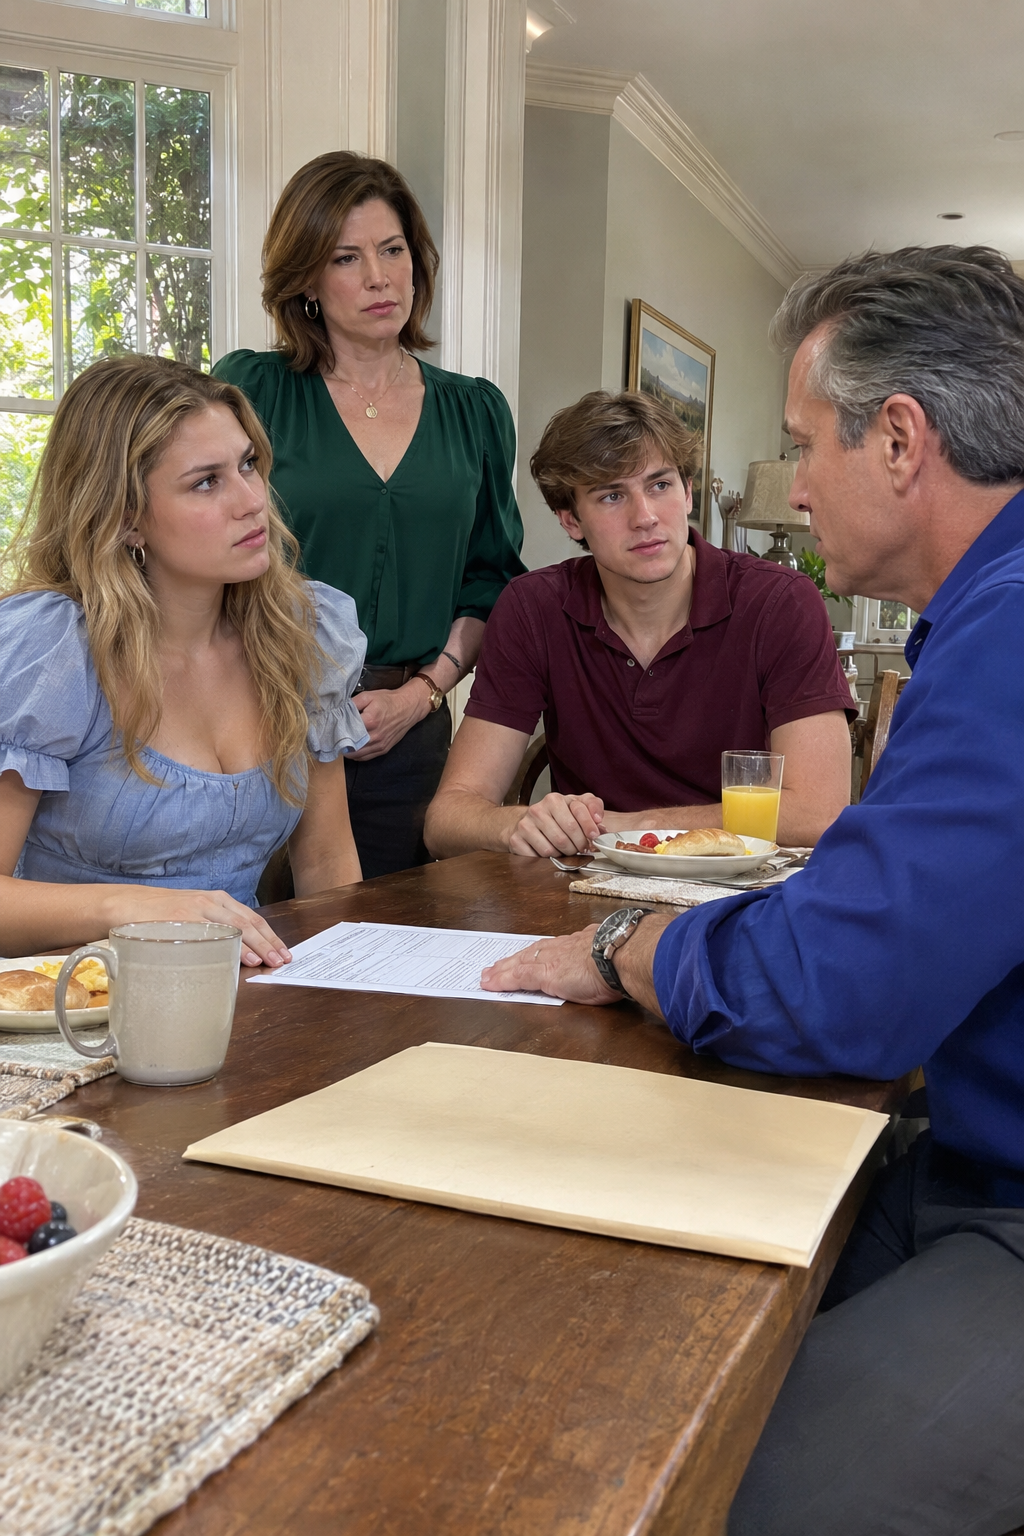
At p.m. on my eighteenth birthday, the trust’s milestone was formally confirmed. I stared at the papers for a long time, thinking of Grandpa and the responsibility he’d tried to prepare me for. The following morning, I came downstairs expecting coffee and an ordinary breakfast, not a contract waiting beside Nolan’s plate.
“Thanks for helping me get the house,” Nolan said, sliding the purchase agreement toward me. “Mom and Dad said everything was already arranged.” Dad’s signature was on the papers, but mine wasn’t, and Mom told me the inheritance belonged to the family and I couldn’t make every decision alone.
I asked which account they meant to use, who had authorized the payment, and why nobody had asked me. Dad said he and Mom had already settled it, while Nolan watched me as if I were holding up his move. I put the agreement back on the table and told them, “Then you should call Marshall Reed before you sign anything else.” For the first time, the silence that followed didn’t feel like mine to fix. Part 2…..
IF FACEBOOK BROUGHT YOU HERE, HERE’S THE CONTINUATION YOU’VE BEEN WAITING FOR. ENJOY! 👇 Nolan stared at the agreement, then looked toward Dad for reassurance. Mom started explaining how families were supposed to help one another, but I wasn’t arguing about generosity. I wanted to know whether they were treating my grandfather’s trust, the company’s bank account, and Nolan’s personal purchase as though they were the same pot of money.
I took my copy of the trust documents upstairs and called Marshall. He asked me not to sign, approve, or promise anything while he checked the papers, and he reminded me that a parent could not replace the authorizations required by the trust or the company’s governing documents. A signature on a purchase agreement might obligate the person who signed it; it didn’t give my father permission to take money from an account he didn’t own.
The question of where Nolan’s deposit had already come from bothered me more than the contract itself. I’d seen unexplained vendor payments before my birthday, but I still couldn’t say those payments had paid for a house. Grandpa’s voice seemed to come back to me: start with the record, not the story someone wants you to believe.
Three weeks after I first noticed the discrepancies, I spoke to my longtime friend Cesaly Brooks about a temporary accounting trainee position. Cesaly had studied bookkeeping and wanted practical experience, so I encouraged her to apply through the normal process. I didn’t ask her to spy or promise her access to files she had no business seeing.
The finance manager interviewed her and hired her for a three-month placement. Her work was ordinary trainee work: entering information from approved documents, sorting invoices, and comparing assigned records with the department’s files. I asked the manager to include a standard reconciliation exercise in the training schedule, with the same supervision and access limits that applied to any other trainee.
During her first week, Cesaly noticed several suppliers with slightly different names but similar contact information. Some invoices appeared to reuse numbers, while others described services without corresponding work records. She took the discrepancies to her supervisor and then showed me the document references she had been assigned to examine.
“This one says the equipment was serviced,” she said, resting a finger beside an invoice number. “But there isn’t a maintenance request in the file.” Another charge was marked as a completed delivery, although the receiving department had no matching entry.
I compared those references with departmental records I was authorized to review. The missing support wasn’t limited to a single mistake or supplier. Payments had been recorded as completed work even when nobody could produce acceptance forms, delivery confirmations, or reports from the employees supposedly requesting the services.
I told Cesaly to keep doing her job and not to make assumptions about anybody. She hadn’t been hired to investigate my family, and I wouldn’t put her in that position. I submitted a written request for an internal control review, listing what was missing without assigning blame, and the finance manager agreed to produce the records through the normal process.
When the approval records arrived, I found several transactions Nolan had approved without the authority those payments required. Other entries showed exceptions Dad had directed, and some supplier descriptions changed from maintenance to consulting to delivery without convincing support from the departments involved. The vendor details looked ordinary at a glance, which made the pattern easier to overlook.
There were also transfers passing through intermediary accounts before reaching recipients connected to people our family knew. A shared surname or an acquaintance wasn’t proof of ownership, much less proof of a crime. I asked the finance manager to obtain bank confirmations through authorized channels rather than treating rumors or screenshots as evidence.
An independent accounting specialist reviewed selected transactions and checked whether the services could be substantiated. That early work separated routine bookkeeping mistakes from invoices that appeared to lack a genuine business purpose. It also showed that established approval rules had been bypassed, including on transactions bearing Nolan’s name.
I brought the records I was authorized to possess to Marshall’s office the following week. He didn’t begin by asking who I suspected. He asked where every document came from, who had approved access to it, and what the company could independently establish from the original records.
Marshall spread the ownership papers and the company’s governing documents across his desk. My grandfather’s trust gave me rights over the inherited interests as its terms took effect, but it didn’t let me order bank employees or accounting staff around just because I was angry. Any restrictions on company payments had to come from the people and bodies legally authorized to impose them.
“A suspicious invoice isn’t the whole case,” Marshall told me. “We need to establish who approved the money, where it went, and what the company received.” He recommended an independent forensic accountant and a formal review through the board, so the findings would not rest on my opinion or Cesaly’s trainee notes.
I made the request through the documented governance process. The board authorized the review, and the accountant obtained records directly from the bank and accounting system using proper company approvals. Employees were instructed to preserve relevant files, and the board added extra checks for unusual payments while disputed suppliers were verified.
Dad called as soon as he received notice. He said I was embarrassing the family and threatening relationships with vendors who had worked with us for years. I said the review would determine which services were real; it wasn’t a vote on whether he and Mom were good parents.
At the office, Dad demanded that Marshall stop treating family disagreements like legal problems. Mom asked if I understood how much damage an investigation could do to all of us. I looked at the records in front of us and told them the company’s employees deserved to know its money was going where the books said it went.
I left without promising to end the review. The people doing the accounting work would check the claims, and the board would make decisions based on their findings. It was the first time I’d sat across from my parents without accepting their word as the final document.
Part 3 The forensic accountant compared bank statements with the general ledger, invoices, purchase requests, and service records. Some errors were harmless and were corrected, but a group of repeated payments could not be tied to work anybody had ordered or received. Several supplier registrations were inconsistent, and approval records showed payments processed outside the limits set by the company.
The accountant also interviewed the managers whose departments were listed on the invoices. Two said they had never requested the services; another remembered a visit but couldn’t confirm the amount billed. Each statement was checked against the original records instead of being treated as proof on its own.
Bank confirmations revealed that some of the questionable payments had traveled through more than one account before reaching accounts linked to people close to our family. The accountant could not identify every account owner from the first set of records, so the report distinguished what had been traced from what remained uncertain. It was painful reading Nolan’s name among the authorizations, but it was worse realizing how casually Dad had weakened the rules Grandpa relied on.
One transfer had a date and amount close to the deposit Nolan had paid on his house. I thought of him at the breakfast table, thanking me for a gift I’d never made. Still, the timing was a reason to investigate, not permission to declare that the entire house was bought with stolen money.
Marshall arranged for the relevant purchase and payment information to be obtained through the proper legal process. The accountant compared bank confirmations, Nolan’s payroll records, and transfers into accounts he controlled. The evidence showed one payment arriving shortly before money went to the closing agent and another linked to a later closing payment.
The investigation also identified amounts Nolan had legitimately contributed. Marshall insisted those be kept separate from the traceable company funds because the business could seek only what the evidence and law supported. I was grateful for that distinction even when Nolan refused to hear it; treating him fairly didn’t mean excusing what the records showed.
Two weeks into the independent review, Marshall had enough documented findings to prepare formal notices. They identified invoice references, approval dates, disputed amounts, and the records recipients needed to preserve or produce. Dad challenged the board’s authority, Mom disputed the implication of her instructions, and Nolan insisted his income and parental assistance explained his purchase.
The final accounting schedule set out unsupported company payments, the people whose approvals or instructions were documented, and the receiving accounts. Communications linked some transactions to Mom, while other entries showed Dad directing exceptions and Nolan approving payments beyond his authority. The company made repayment demands tied to each person’s documented involvement instead of charging every family member with every missing dollar.
Nolan came to a formal meeting carrying copies of his house papers. He pushed the documents across the table and said, “You can’t take my house. I signed the contract.” His voice was steadier than his hands, and for a moment I remembered him as the little boy who used to follow Dad around the office.
Marshall explained that a signed purchase agreement did not wipe away the source of the purchase funds. It also didn’t mean an audit could automatically cancel a house sale or seize the property. Any claim against Nolan’s interest would have to be established in a lawful proceeding and limited to what the tracing actually supported.
“Some of that money wasn’t yours, Nolan,” I said. He looked at me as though I’d chosen a stranger over him, but I couldn’t change the bank records by calling this a family favor. The company began its civil recovery process, with the house-related claim separated from Nolan’s documented personal contributions.
Pierce and Harriet received their own demands covering transactions tied to their decisions. Company counsel also considered whether the evidence should be referred to the proper authorities, who would decide independently whether further action was warranted. I never claimed that an investigation meant anyone had already been convicted of anything.
Fallon called and said I was tearing the family apart. I asked whether she had approved any invoice, transferred any money, or even seen the supporting records; she said she hadn’t. The review checked relevant records but found no basis to demand repayment from her simply because she had taken our parents’ side.
Meanwhile, the board completed the resolutions necessary for me to assume the management and ownership responsibilities permitted by the trust and corporate documents. Nolan’s access to financial systems was suspended when he no longer had a legitimate business need, and unauthorized payment privileges were removed. No one was barred from accounts merely because I disliked them; the controls had to apply to everyone.
We required separate preparation and approval for significant payments, verified changes to vendor details independently, and demanded evidence of completed work before service bills were paid. An outside firm began regular reviews, and department managers were asked to confirm their actual suppliers. I signed the revised policy only after the board approved it, knowing it would apply to my decisions as much as anyone else’s.
Some money came back quickly when responsible parties agreed to repay transactions whose records were clear. Other amounts remained disputed, and counsel tracked them as open claims instead of counting promises as repayments. Each month the board received a schedule of confirmed losses, actual deposits returned, pending claims, and unresolved exposure.
Dad and Mom lost their operational authority after the governance changes were completed. They could no longer override the finance department or instruct employees to overlook missing paperwork. It wasn’t the end of the recovery effort, but for the first time the company had procedures that didn’t depend on whether someone happened to be a Whitlock.
Final By the final stage of the recovery process, the company had recovered most of the money the forensic accountant could trace to unsupported invoices. Some recipients paid after formal demands, and others reached settlements approved by the board. A smaller disputed amount remained open, so we kept it listed as a claim rather than pretending every dollar was already back.
The question of Nolan’s house also reached a formal resolution. The court accepted evidence that part of his deposit and closing payment came from company funds routed through accounts connected to him, while recognizing his legitimate contributions separately. The resulting recovery was limited to the traceable portion of his interest, not the entire value of the home.
Nolan had to refinance under new terms and repay the company the amount established by the judgment. The house he once spoke about so casually became a responsibility he had to manage without Dad fixing it for him. I didn’t celebrate that, and I didn’t offer to make the obligation disappear.
Dad and Mom were required to repay amounts assigned to them under a settlement based on their documented approvals and instructions. They no longer had authority over company operations or access to its financial systems. The authorities’ separate review of their conduct remained ongoing, with any additional consequences dependent on that process.
Mom called more than once asking me to withdraw the complaints and work something out privately. I told her I couldn’t bargain away the company’s rights at our kitchen table. The employees who showed up every morning, the customers who depended on us, and the suppliers who had actually done their work all had a stake in how we handled the losses.
Nolan stopped getting financial help from our parents once they understood how much exposure their own decisions had created. He was angry with me for a long time, and we didn’t repair things by pretending the transfers were ordinary family gifts. I could care about him and still expect him to answer for what had happened.
Fallon eventually admitted she hadn’t known where the money came from. The review found no evidence that she’d approved payments or knowingly hidden the transactions, so the company made no claim against her. But she’d dismissed my concerns at every step, and when she wanted us to act like nothing had happened, I told her I needed distance.
Running the business turned out to be less dramatic than confronting my family and far more demanding. We still had payroll to meet, contracts to honor, equipment to maintain, and customers waiting for their orders. Independent directors reviewed major decisions, bank activity was reconciled every month, and no relative received access simply because of a last name.
One afternoon I read the final accounting report beside the trust documents Grandpa had signed. I remembered his patience when I found that duplicate delivery charge, and the way he’d made me explain every number before deciding what it meant. He hadn’t prepared me to win an argument with my parents; he’d prepared me to be responsible for other people’s livelihoods.
Harriet came to see me after the report was issued. “After everything we’ve done for you, you’re really choosing a company over your family?” she asked, keeping her hands folded around her purse. I told her, “You made that choice when you used Grandpa’s company to pay for things that didn’t belong to you.”
Marshall later sent a written summary of what had been recovered, what remained outstanding, and who was responsible under the completed agreements and judgment. I signed the acknowledgment and put it with the permanent company records. I didn’t call my parents afterward, because there was nothing left that should be settled outside the proper process.
I still miss the family I thought we were. But I don’t confuse keeping quiet with keeping peace anymore, and I won’t call an honest accounting an act of revenge. Grandpa left me three million dollars’ worth of responsibility, and the part I treasure most is what he taught me to do when the numbers, and the people I loved, didn’t tell the same story.
THE END. I’ve shared the complete story, and I truly hope it touched your heart. If this story moved you, please , like, and share the post. Thank you for reading! ❤️
✓ Lynn R. Adams
The morning after I turned eighteen, my younger brother thanked me for buying him a house I had never agreed to pay for, and my father’s signature on the purchase agreement made me question everything…