Chapter 5: THE PROOF THAT TURNED THE TABLES
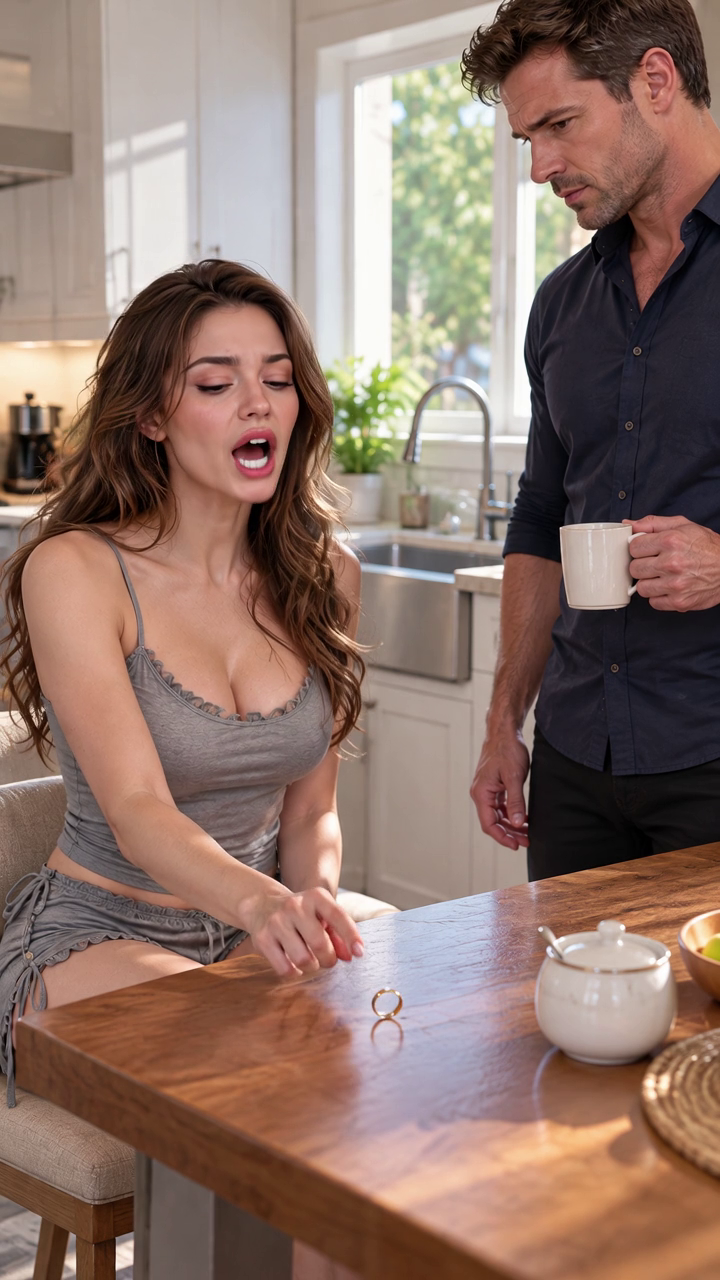
One hundred eighty thousand dollars was the amount somebody had tried to borrow using my name and our house.
I couldn’t decide which part terrified me more: the money or the possibility that my signature was already floating around somewhere I’d never seen.
I asked the lender to stop the application and open an identity-fraud review.
The representative confirmed it had been flagged before funding and gave me a case number.
She told me to submit a written dispute and an identity-theft report so the institution could preserve and investigate the application records.
I called Samantha immediately.
“Don’t contact Evan,” she said.
“Don’t threaten Lauren, and don’t start announcing fraud in the neighborhood chat.”
“I wasn’t going to.”
“You’re angry, Michael.”
“You have every reason to be.”
“But right now, you’re also a witness.”
She walked me through contacting the police nonemergency line and documenting the lender’s response without claiming to know who submitted the application.
I filed the identity-theft report and preserved the credit alert, phone notes, and loan reference number.
The detective who took the report didn’t promise arrests.
She said the lender and its records would have to be examined.
I appreciated that answer more than I would have appreciated empty assurances.
During a follow-up interview, the detective asked me whether I’d ever handed Evan a copy of my identification.
I said I hadn’t.
She asked whether I’d ever discussed borrowing against the house with Lauren or Evan.
I told her about the coffee-shop conversation and my refusal, then gave her the date and the note I’d written afterward.
She didn’t tell me which of my answers mattered most.
She asked me to keep the original documents and not delete any communication that might later look embarrassing.
“People sometimes tidy up their own stories without realizing it,” she said.
“Don’t.”
Some of those messages showed how we normally made major financial decisions together.
Others showed that we had disagreed over expenses long before Evan entered our lives.
I didn’t need a record of a perfect marriage.
I needed an honest record of the one we’d actually had.
The detective said the investigation would have to follow documentary evidence wherever it led, including Lauren’s conduct.
I told her I understood.
For the first time, I really did.
Then I went to Sophie’s Thursday art show.
I had promised her I would be there, and I wasn’t breaking another promise because adults were destroying each other’s finances.
Lauren arrived just as the children began explaining their paintings.
She stood near the back, pale and uncertain, holding a bouquet of grocery-store daisies.
Sophie ran to her before I could decide what to say.
For a moment, they hugged like nothing had changed.
I watched without interrupting.
Our daughter had painted our old kitchen window, the sunflower magnet, Milo asleep underneath it, and three tiny figures at the breakfast table.
The third figure was her mother.
Lauren saw the picture and began crying.
Sophie frowned.
“You’re supposed to be happy,” she said.
“I am,” Lauren answered.
“It’s beautiful.”
We took separate photographs with Sophie because that was what she wanted, then stood together for one more when she asked.
We didn’t touch.
I could feel Lauren waiting for me to say something about the loan, but I refused to turn our daughter’s school into a courtroom.
Outside, after Sophie left with Mia for ice cream, Lauren approached me.
“You got a call from a lender,” she said.
“How would you know that?”
“Evan told me they had questions.”
My jaw tightened.
“Did you give him my documents?”
She stared at the parking lot.
“I sent him a copy of the mortgage statement and a photograph of your driver’s license.”
“Why?”
“He said a financial advisor needed them to check what the house might qualify for.”
“Did you know he was applying in my name?”
“No.”
“Did you tell him I agreed?”
“No.”
“Then don’t try to fix this by asking me to forgive it.”
She cried again, but this time I heard myself say something calm.
“Give those messages to your lawyer.”
“Every one of them.”
“You’re going to need them.”
The next two weeks were less dramatic than that conversation and more exhausting.
I worked my usual shifts, picked up Sophie, reviewed bank paperwork at night, and learned how many hours it took to prove what hadn’t happened.
Samantha filed the divorce petition and sought temporary orders addressing household expenses and parenting arrangements.
Lauren retained her own lawyer, who advised her to stop communicating with Evan about the association investigation.
The lawyers negotiated a temporary schedule that kept Sophie at the family house for school nights and gave Lauren regular time with her.
We used a shared written calendar for pickup times so Sophie never had to carry messages between us.
The bank opened its own review of the joint-account transfers but didn’t promise reimbursement, since Lauren had initiated them through an account she was authorized to use.
Our insurance agent couldn’t tell me whether any possible losses were covered until there was a formal determination.
The family’s finances remained damaged, and that was part of the reality no headline could erase.
Meanwhile, Grace and the association board hired an independent forensic accountant.
He compared vendor invoices against board approvals, bank disbursements, contractor records and photographs of completed work.
A preliminary report identified more than one hundred forty thousand dollars in suspicious payments over eighteen months.
That figure was not yet a proven theft total, and the accountant marked it as subject to reconciliation.
But he documented payments for repairs without corresponding work orders and duplicate invoices bearing different dates.
Cedar Lane Partners appeared repeatedly.
The board suspended future payments to the company and asked its counsel to preserve relevant files.
Grace convened a meeting open to residents where the board explained the steps being taken without publicly declaring anyone guilty.
Evan attended, smiling tightly.
He insisted Cedar Lane had performed legitimate work and accused Grace of weaponizing an audit to win a neighborhood election.
I sat in the back and listened.
When he said the work orders were available for inspection, Grace asked him to provide them to the accountant.
He promised he would.
He didn’t mention my wife.
Afterward, he approached me in the parking lot.
“Sorry about your family problems,” he said.
I looked at the man who had borrowed my ladder, greeted my daughter by name, and possibly watched my marriage collapse on a screen.
“Don’t talk about my family,” I said.
His smile disappeared.
“You should be careful about believing what people tell you.”
“I am,” I answered.
“That’s why I’m letting the records speak.”
I walked away before my anger could give him a better story to tell.
The audit affected people whose names hadn’t appeared in our marriage argument.
An elderly neighbor named Ruth had been paying extra association assessments while postponing repairs to a leaking bedroom ceiling.
A young couple across the street had saved for a special assessment because they’d been told the retaining wall couldn’t wait.
Nobody had asked them to invest in Evan’s dream or finance his private spending.
They’d paid dues because they believed the association would maintain the places their children played.
At the residents’ meeting I saw that my betrayal wasn’t the only one the neighborhood was dealing with.
I also saw how easily anger could become reckless.
One man proposed posting Evan’s picture on every community noticeboard with the word thief underneath it.
Grace refused.
“We have a report,” she said.
“We have referred the concerns to the authorities.”
“We don’t have a conviction.”
That restraint frustrated some people, including me for a moment.
Then I remembered the lawyer’s warning about evidence and how much harder a case could become if every person involved started making their own accusations.
Tessa sat beside me, two rows from the front.
She had moved with her son to her sister’s house and was arranging her own legal advice.
“Everyone thinks I should have known,” she whispered.
“I lived with him.”
“I lived next to him,” I said.
“And I called him a good neighbor.”
She gave a small, tired laugh that sounded nothing like amusement.
A week later, the camera company delivered the account export I had requested.
It confirmed that Lauren’s household account had issued a guest invitation to an address controlled by Cedar Lane Partners.
The guest had accepted it, and the service recorded multiple viewing sessions, including one during our Tuesday argument.
The log didn’t display a human face behind the computer.
By itself, it could not identify who was watching.
But it established that our family’s private kitchen feed had been accessed through the guest account when that message arrived.
Lauren’s lawyer then provided investigators with a preserved export of her messages with Evan, which she had agreed to share.
She made no demand that I drop the divorce in exchange.
The conversation showed Evan repeatedly pressuring her to leave me and promising that Cedar Lane would repay the money after an upcoming property sale.
It also contained the message from that Tuesday morning.
“He poured it out.”
It was sent from a number Lauren identified as Evan’s, at the same time the guest account was actively viewing our kitchen feed.
Investigators still had to authenticate the underlying records and subscriber information.
But the coincidence that had once seemed impossible now had a documented explanation.
Evan had a way to watch us, and a message attributed to him described something only a watcher could have known.
Lauren also supplied the texts in which he asked her to send my license and mortgage statement.
I felt sick when Samantha summarized them.
Evan had called the loan a “bridge” until his supposed property deals closed.
He had told Lauren she’d already risked too much to back out.
When she asked whether I needed to sign anything, he replied that he’d handle the paperwork.
Those messages did not automatically prove he submitted the application.
They did show intent to obtain financial information and a plan he hadn’t disclosed to me.
Then the lender’s fraud investigator confirmed that the application used a digital signature attributed to me, even though I’d denied applying.
The lender preserved the submission details for law enforcement and confirmed that no funds had been released.
That distinction mattered.
We were facing an attempted loan, not a new debt I suddenly owed.
At last I could separate the financial damage already done from the disaster that had narrowly been prevented.
The independent accountant’s fuller report arrived next.
It found that payments to Cedar Lane exceeded the value of documented association work by a substantial amount, while some claimed jobs lacked any evidence of completion.
It also showed that several approvals had been generated using Lauren’s work account.
Lauren admitted she’d clicked them and accepted responsibility for failing to verify the work.
She said Evan had instructed her to treat several missing documents as temporary administrative errors.
Her cooperation didn’t erase the damage or guarantee she wouldn’t face consequences.
It did prevent Evan from presenting the entire transaction history as if she had acted alone.
The board referred the findings to law enforcement and began consulting counsel about possible recovery.
Our family lawyer used verified bank records and Lauren’s documented transfers to seek proper financial accounting in the divorce.
For the first time since the ring had spun across the table, I wasn’t relying on a guess or a frightened look.
I had records, dates, admissions, and professionals whose job was to test them.
Then Samantha called with one last development.
Evan’s attorney had filed a written declaration in related civil proceedings about Cedar Lane’s business transactions.
It claimed Lauren had obtained the household money with my knowledge.
It claimed the proposed home-equity financing had been my idea.
And it carried Evan’s signature beneath a statement that his account was true.
The man who had watched my humiliation was now trying to make me responsible for his plan.
👉 The story isn’t over yet—tap NEXT to find out what happens in the next chapter! 🔥
✓ Lynn R. Adams
One hundred eighty thousand dollars was the amount somebody had tried to borrow using my name and our house. I couldn’t decide which part terrified me more: the money or the possibility that my signa…