CHAPTER 4 – The House Was Part of Her Secret Plan
For several seconds, nobody in Mara Ellis’s office moved.
My wife sat beside me with her phone trembling in both hands. On its screen, Grant’s message still waited beneath our conversation: You need to tell him about the second authorization before someone else does.
“Show us,” Mara said.
My wife swallowed. “I don’t know if I still have it.”
“Then start with what you remember.”
She looked at me, perhaps expecting the familiar version of her husband to rescue her from a difficult conversation. I had done that for years. Whenever she was overwhelmed, I offered solutions before she had to ask for them. But this time, the problem was something she’d done to me.
“Grant emailed me a link while we were in Room 614,” she said. “He said the application couldn’t move forward unless the second owner approved the preliminary review.”
“And you told him I hadn’t approved it,” I said.
“Yes.”
“What did he tell you to do?”
She pressed her thumb against the edge of her phone. “He had set up an email address with your name. He told me to open the link there and confirm that you had authorized the review.”
Mara leaned forward. “What did you actually click?”
“A box that said I was the named applicant. Then an electronic consent button.”
“Were you the named applicant?”
My wife’s answer was almost inaudible. “No.”
“Did your husband authorize you to act for him?”
“No.”
The confession landed without shouting or drama. A paper cup sat on Mara’s desk beside a stack of files. I remember staring at it because I couldn’t bear to look at the woman next to me.
For eleven years, she’d known my habits, my worries, the exact way I took my coffee. She’d taken that familiarity and allowed a stranger to turn it into a substitute for my consent.
“Did you understand you were representing yourself as me?” Mara asked.
“I understood what the form said,” my wife whispered. “Grant said it wasn’t a loan agreement. He said we’d still have to sign final papers together.”
“That may be true about final loan documents,” Mara replied, “but consent to an inquiry or an appraisal is still consent. Your husband didn’t give it.”
I finally turned toward my wife. “You told me you didn’t sign my name.”
“I didn’t write your signature.”
“You clicked a button saying you were me.”
She closed her eyes. “Yes.”
It was a distinction she had been hiding inside since the night before. I had asked the wrong question, and she’d used the narrowest possible answer to keep the truth from escaping.
Mara asked her to find the message containing the link. She searched her email and recovered it from an archived folder. The subject line referred to a co-owner verification request. The sender’s address belonged to a document service, not to the mortgage company that held our existing loan.
Mara photographed nothing herself. She had my wife save the original email and forward it, with its attachments intact, to the secure address her office provided. Then she asked us to write down which devices we’d used and when we’d been at the hotel. She wanted a clean record of what we knew, what we believed, and what still needed verification.
“Don’t erase anything,” she told my wife. “And don’t try to solve this by privately negotiating with Grant. You can tell the investigator exactly what happened. But you need your own legal advice about your role in it, separate from your husband’s interests.”
My wife stared at her. “Am I going to be arrested?”
“I can’t predict that,” Mara said. “My immediate job is to protect my client’s interests and help him challenge any unauthorized activity. You should speak with independent counsel before making further decisions.”
That was the moment my wife seemed to understand that an apology would not put us back at yesterday morning.
I asked Mara about the amount shown in the preliminary application. It wasn’t fifty-two thousand dollars. It was almost one hundred and forty thousand.
My wife tried to explain. “Grant said the larger figure would cover Caroline’s debts, fees, and enough working capital to keep the store open. He called it a cushion.”
“A cushion secured by our home,” I said.
“He said we wouldn’t have to take the full amount.”
“And you agreed to let him apply for it without asking me.”
She didn’t answer.
Mara clarified that the form on the screen appeared to be an application and consent package, not proof that a loan had closed. We still needed the lender’s audit records, a confirmation of the application’s status, and a check for any recorded documents affecting the property. I felt some relief, but it was an uncomfortable kind. Being told a fire might not have spread beyond one room didn’t make me grateful somebody had lit the match.
Before we left, Mara helped me finish a written dispute. I stated that I hadn’t authorized any application, electronic signature, appraisal visit, or use of the invented email account. The office would send the notice through verified channels and request records. She also recommended that I report the suspected identity misuse through the appropriate consumer-reporting process and preserve all reference numbers.
My wife offered to sign the same statement.
“Not without your own lawyer reviewing it,” Mara told her. “And whatever you say must be accurate.”
We walked out of the office separately, just as we’d arrived. Outside, the October sunlight was bright enough to make me squint. People were crossing the parking lot with grocery bags and coffee cups, going about lives that still made sense to them.
My wife stopped beside my car. “There wasn’t an affair,” she said.
I looked at her. “I haven’t said there was.”
“You thought the hotel meant another man. I need you to know I never slept with Grant.”
I believed she might be telling the truth. It didn’t bring the relief she wanted.
“You let him speak for me,” I said. “You gave him my information, my signature page, and a way to pretend I agreed. Whatever happened in that room, he walked out knowing more about our house than I did.”
She began to cry. “I was trying to help Caroline.”
“I know. That’s what makes it worse. You decided loving her required lying to me.”
I got into my car. She didn’t ask to ride with me.
At home, I opened the cabinet where we kept our closing documents. I spread the papers across the living-room floor, the same floor where we’d eaten pizza on the day we moved in. There were mortgage statements, insurance policies, receipts for the upstairs paint, and the first picture we’d taken of ourselves beside the front door.
In that photograph, my wife was laughing with her head tilted against mine. The house keys were hanging from my index finger. We’d worked so hard to earn a place we could call ours. Neither of us had imagined that one day the question would be whether the other had the right to make decisions about it alone.
I checked the county recorder’s public index using our address and names. I didn’t find a new recorded mortgage or lien. I saved a dated copy of the search result, then reminded myself of what Mara had said: a public search wasn’t a promise about what might be filed later. We would need to check again and obtain confirmation from the institutions involved.
I froze my credit with the major bureaus, changed passwords, and enabled additional security on the accounts I controlled. I didn’t touch my wife’s separate accounts or pretend our joint money had suddenly become mine. We still had a mortgage payment due, utility bills to cover, and a house to maintain while lawyers sorted out what was ours individually and together.
That evening, Caroline came over. She arrived without makeup, wearing a sweatshirt under her coat. My wife was sitting at the far end of the couch, holding a glass of water she hadn’t touched.
Caroline stopped inside the doorway. “I told her not to do it,” she said to me.
“I believe you told her to stop when Grant asked for money,” I replied. “I need to understand what happened before that.”
She nodded. Her store had been failing for months. She’d hidden the worst of it because she was embarrassed and afraid people would tell her to close. When Grant offered a possible solution, she passed his name to my wife. She admitted she’d hoped somebody else would find the answer she couldn’t.
“I thought he was a real lending consultant,” Caroline said. “I didn’t know he wanted her to keep you out of it.”
“Did you ever receive any of the money?”
“No. I haven’t received a dollar.”
“And the four thousand eight hundred?”
Caroline looked at her sister. “I told you that fee was suspicious.”
My wife stared into her glass. “He said it would be credited back at closing.”
“He said a lot of things,” Caroline replied.
It was the first time I’d heard Caroline speak to her without softening every word. They had always protected each other, sometimes by refusing to acknowledge when protection had become permission. Now even that loyalty had a limit.
Caroline told us she was preparing to close the store. Her landlord had offered to discuss an early termination, and she was speaking with a business adviser about the remaining debts. Nothing about it was painless. She might lose the business she’d spent years building. But she had finally stopped pretending another person’s house could make the arithmetic disappear.
“I’m sorry I brought Grant into your lives,” she told me.
“You introduced him,” I said. “She made the decisions afterward. Those are two different things.”
My wife put down her glass. “I know.”
I wanted to ask why knowing had arrived so late. Instead, I asked Caroline to send Mara’s office the messages she’d preserved after obtaining her own advice. She promised she would.
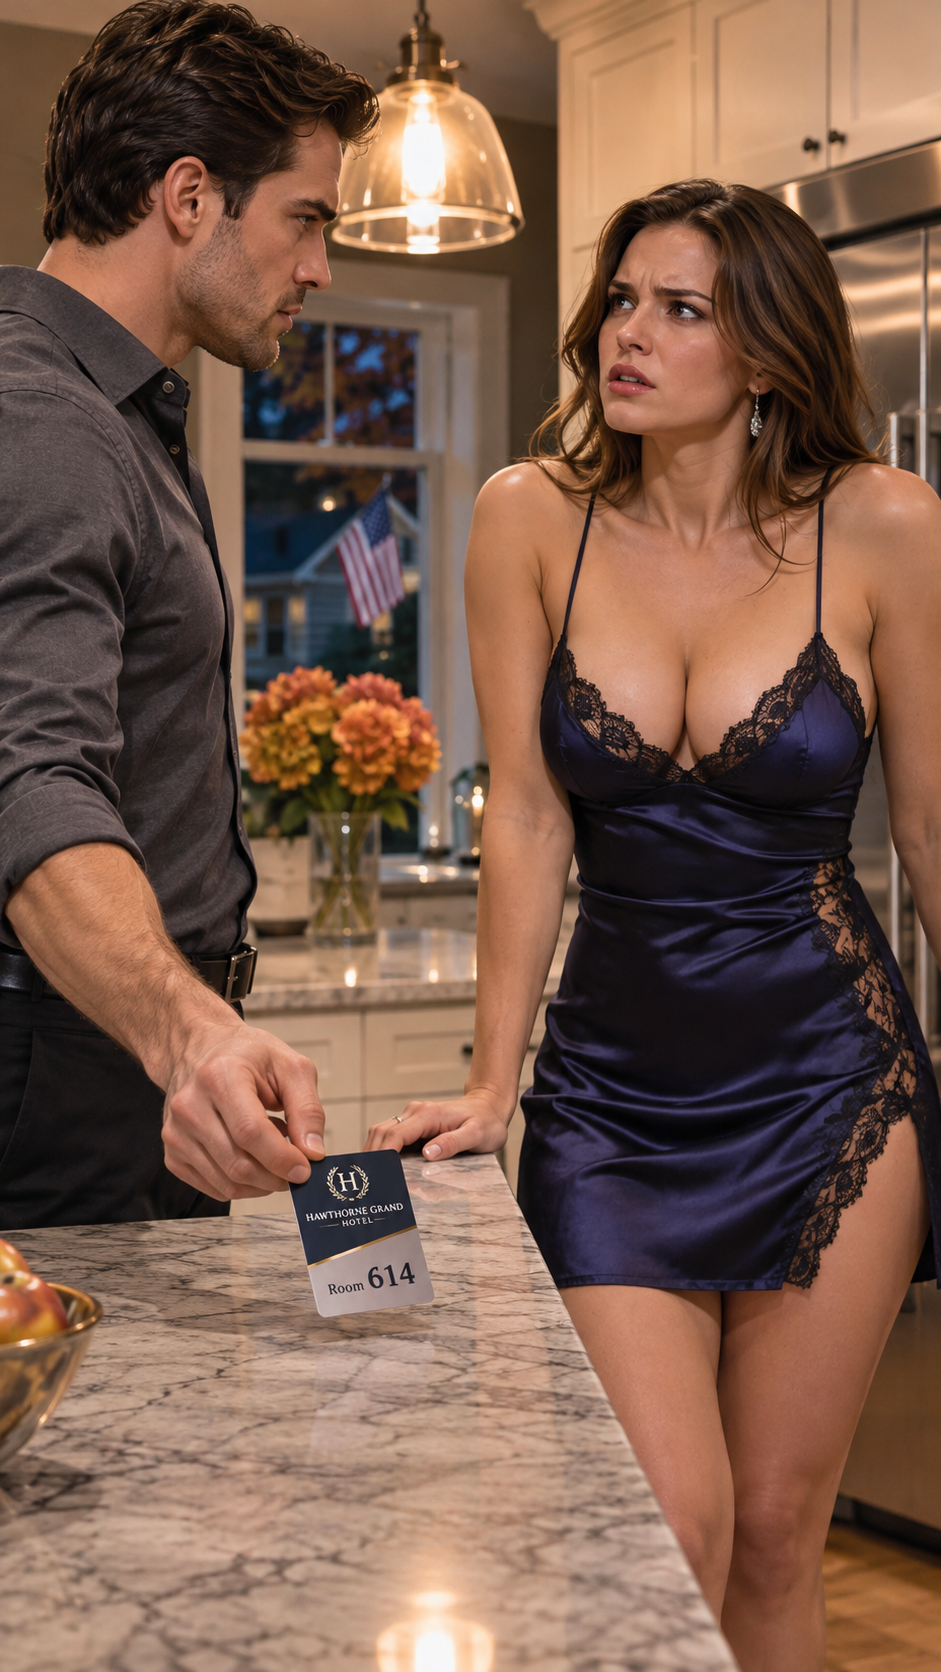
Later, after Caroline left, my wife and I stood in the kitchen where the argument had begun. Room 614 still lay in its place on the counter. I had sealed it in a clear document sleeve so it wouldn’t be handled or misplaced.
“I called Grant after you went upstairs that first night,” she said.
“I figured you did.”
“I told him you found the card. He said not to tell you anything until the appraisal was complete. He told me you would panic and ruin the arrangement.”
“And when I asked about the house?”
“I couldn’t keep lying anymore. But I was scared to admit what I’d already done.”
I looked at the sleeve. “Why did you keep the card?”
She gave a miserable little laugh. “I forgot it was in the car. I wasn’t planning to keep a souvenir.”
I nodded. The answer was ordinary, almost embarrassingly so. I’d spent a whole night imagining a secret relationship because I’d found a hotel key. The real secret was documents and numbers and someone I’d never met using my name with my wife’s help.
“I need you to stay with Caroline for a while,” I said.
She looked up sharply. “You’re throwing me out?”
“No. I’m asking for space. This is your home, too, and I know you have rights here. But I can’t share a bedroom with you right now, and I don’t want another week of conversations where I have to pull the truth out one sentence at a time. If you don’t want to leave, we’ll work out another arrangement.”
She considered that. Then she nodded. “I’ll go.”
“We should put practical things in writing with advice from our lawyers. Mortgage payments, household expenses, access to the house. No surprises.”
“Okay.”
She walked upstairs and returned with an overnight bag. I heard her move through the rooms we’d painted together. Each quiet footstep hurt more than the dramatic exit I’d half expected. When she reached the door, she turned.
“Can you ever forgive me?”
I didn’t answer quickly. “I don’t know what forgiveness will look like. I do know I can’t keep living as though trust is the same thing as not asking questions.”
She nodded, stepped onto the porch, and closed the door gently behind her.
The next several days were full of calls that rarely ended with satisfying answers. The financial company acknowledged my written dispute, suspended its review, and requested additional information through a verified process. Its fraud team was examining the electronic-signature and account-access records. My existing mortgage servicer confirmed again that my regular loan was current. Neither conversation proved that nobody else had received our documents, but both gave me something concrete to record.
My bank opened a review of the payment from my wife’s separate savings account after she reported it herself. Recovery wasn’t guaranteed, and no one promised a quick refund. Caroline preserved her messages. Mara helped coordinate the financial dispute while reminding me that the marriage itself was a separate legal matter.
I also scheduled a consultation with a family-law attorney. I didn’t file for divorce that afternoon. I wanted to understand our responsibilities, the house, the mortgage, and what a separation would mean before making another irreversible choice. For once, I was going to make a decision with my eyes open.
The first written response from the lender came six business days after our visit to Mara’s office. The application had been withdrawn from consideration following the identity dispute. The lender stated that it had not funded a loan under that application and had not recorded a mortgage connected to it. The company was continuing to review how the electronic consent had been obtained.
I read the letter three times. Then I called Mara to confirm what it did and didn’t mean. She told me it was important progress, not a reason to stop monitoring our records. We would keep the correspondence and follow up on any remaining questions.
A separate response from the coordinating firm explained another part of the mystery. Grant had submitted our information as an outside referral, not as an employee empowered to verify borrowers. The firm said its procedures did not authorize a referral agent to create an email account in an applicant’s name, and it had no record of approving the processing payment. It would preserve its files for review. Those statements did not establish exactly where our money had gone or guarantee that every copy of our documents had been recovered. Mara asked the firm to preserve its audit records and advised us to report the suspected impersonation to the appropriate authorities. We did. I wrote down the report number, folded the correspondence, and put it beside the hotel card. For once, the paperwork was helping me understand what had happened instead of hiding it.
For the first time since I found the card, I walked into the kitchen and didn’t immediately feel that the floor might disappear beneath me.
That relief didn’t repair the marriage.
My wife came by the following Saturday to collect clothes and some personal things. We had agreed on the time, and I was home. She looked tired. I probably did, too. We were careful with one another in the way strangers are careful in a narrow hallway.
She told me she had contacted independent counsel and was cooperating with the reviews on advice. She wasn’t asking me to make promises about what the outcome would be. I appreciated that more than another speech about how she’d only meant to help.
“I keep thinking about the night we moved in,” she said.
“The pizza?”
She nodded. “You said it didn’t matter how long it took us to pay for this place, as long as we made the decisions together.”
I remembered saying something like that. The room had been empty and our future had seemed manageable because it belonged to both of us.
“I should have called you before I sent the first document,” she said. “I should have stopped when Grant told me to use that email address. I knew you’d say no, and I decided that meant I had to make it happen before you could.”
It was the first apology she’d given me that didn’t ask me to misunderstand the facts. I could hear the difference. She wasn’t blaming Caroline, Grant, or my caution. She was finally naming her own choices.
“Thank you for saying it plainly,” I told her.
She held my gaze. “Is there any way back?”
I looked around the kitchen. I loved parts of the life we’d made here. I loved the memories in the walls and the version of us that had once trusted each other with ordinary, unglamorous decisions. But loving a memory wasn’t the same thing as being able to live inside it.
“I don’t know whether I’ll ever trust you again,” I said. “And I won’t promise to try just because the paperwork might be fixable.”
She pressed her lips together, accepted the answer, and picked up her bag.
After she left, I took the hotel card out of its sleeve long enough to read the number once more. Room 614. Nothing about those three digits had changed. Only what I understood them to mean.
I’d believed the worst thing a spouse could hide was another person. I learned there were other ways to make someone a stranger in his own home: an email address created in his name, a form checked without his permission, a decision made about the roof over his head while he was still coming home to it every night.
I returned the card to the sleeve and placed it with the records for Mara. Then I opened the curtains and let the late October sunlight into the kitchen.
The house was still standing. The mortgage was still ours. The damage between us would take longer to understand.
But from that day forward, nobody would speak for me about my home without my consent. And whatever happened to my marriage, that decision would be mine.
✓ Lynn R. Adams
For several seconds, nobody in Mara Ellis’s office moved. My wife sat beside me with her phone trembling in both hands. On its screen, Grant’s message still waited beneath our conversation: You need …