CHAPTER 3 – The House Was Part of Her Secret Plan
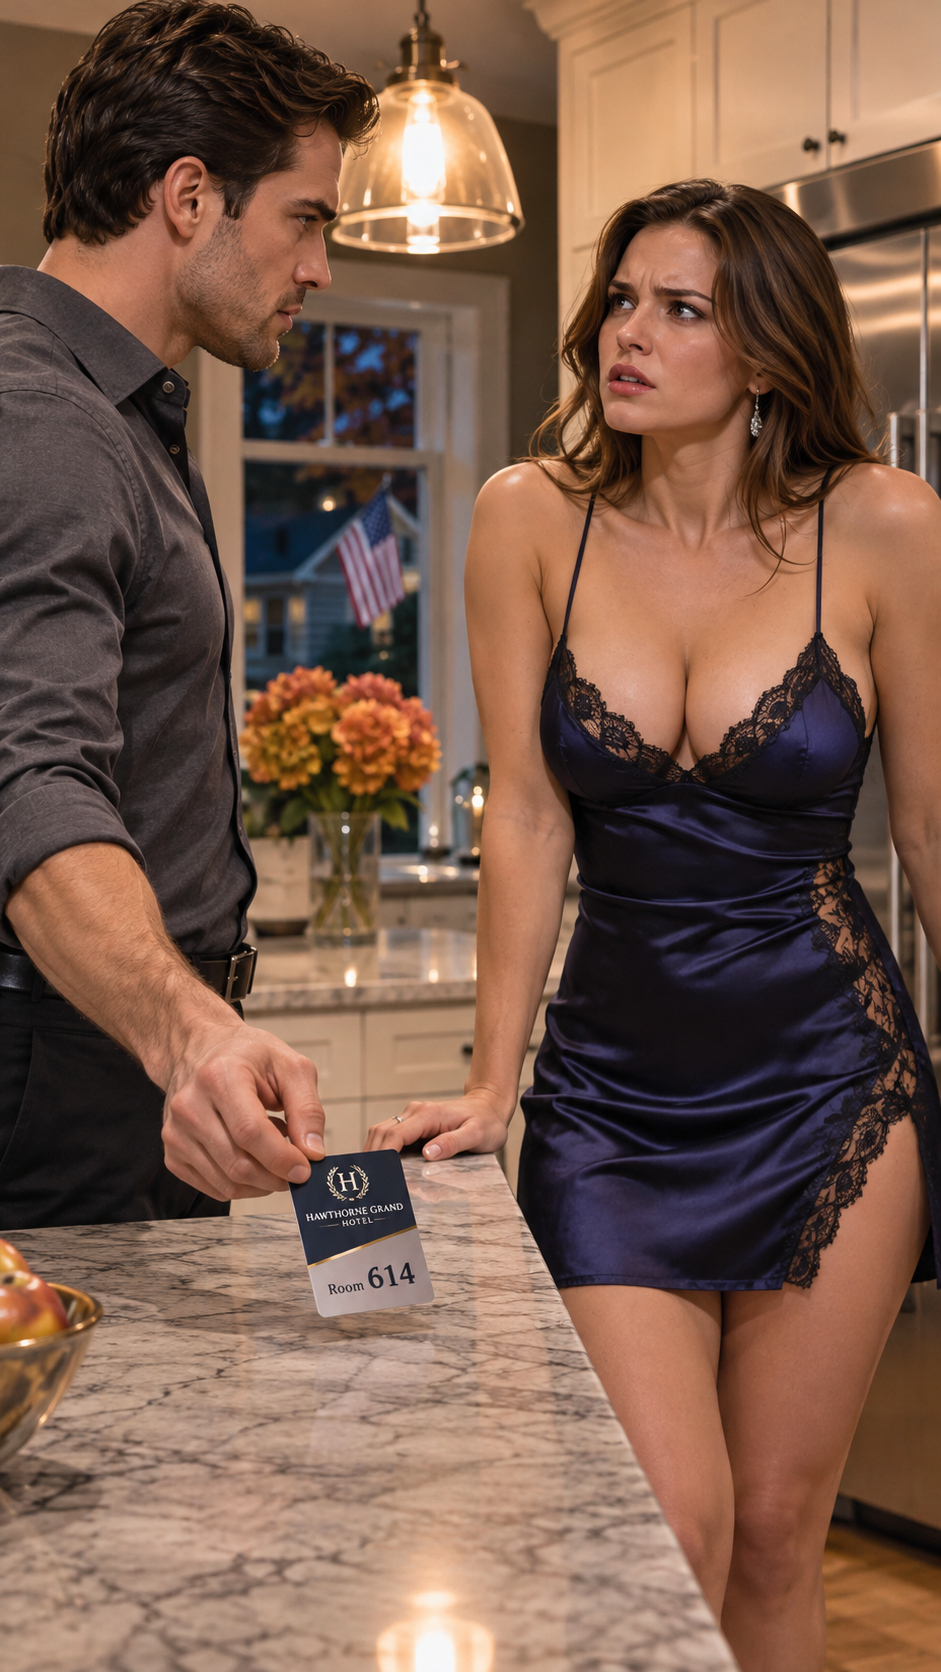
The appraiser stood on our porch holding a work order with my name on it. Behind me, my wife gripped the doorframe. She had sworn she hadn’t signed anything for me, yet somebody had apparently confirmed an appointment using my identity.
“I need you to mark this visit as disputed,” I told him. “I didn’t authorize an inspection, and nobody has permission to enter.”
He looked relieved to have a clear instruction. “I’ll notify my office and put the job on hold. I’m sorry. I was given an ordinary residential assignment.”
“I understand. I don’t think you knew anything was wrong.”
He gave me a business card and the assignment reference number. He wouldn’t hand over another client’s private paperwork, but he agreed to record that I had personally challenged the authorization. I watched him make the call from his car before he drove away.
When I shut the door, my wife was still standing in exactly the same place.
“Did you tell Grant he could pretend to be me?” I asked.
Grant was the first name she’d finally given me that morning. She had described him as an adviser, although she couldn’t provide a company address, a license number, or a single document explaining what he was authorized to do.
“No,” she said.
“Did you tell him I knew?”
She glanced toward the kitchen. “I said you’d understand once everything was arranged.”
“That’s not the same thing.”
“He told me the appraisal was preliminary. He said nothing could actually happen without both of us signing.”
“Then why did he say I approved a visit?”
She rubbed her hands together. “I don’t know.”
I believed she didn’t know everything. What frightened me was how much she had chosen not to ask.
I went back to the island. The hotel key card had barely moved since I’d put it there the night before. Its black surface looked almost elegant beneath the pendant lights, the number 614 shining silver near the bottom. My wife followed me but stayed on the opposite side.
“We’re going to separate what you know from what he told you,” I said. “And we’re going to write it down.”
“You’re treating me like a criminal.”
“I’m treating our house like something worth protecting.”
I took a notebook from the drawer where we kept spare batteries and grocery coupons. I dated the page. Then I asked her to begin with the first time she heard Grant’s name.
Her sister, Caroline, had introduced them by phone two months earlier. Caroline was trying to keep her small home-decor business afloat after losing a commercial client. An overdue supplier bill had become several overdue bills, and she was frightened that closing the store would leave her personally responsible for money she couldn’t repay.
“Why didn’t you tell me?” I asked.
“Because you would have said we couldn’t save her.”
“I would have wanted to see the numbers.”
“That’s what I mean. You’d have turned her into a spreadsheet.”
I nearly answered with the obvious truth: a spreadsheet was exactly what she needed before anyone risked a home. But the accusation sounded familiar. When we disagreed about money, my caution became a character flaw, as if asking for a total meant I didn’t love her family.
“How much did Caroline need?”
“Thirty-eight thousand dollars at first.”
“At first?”
“There were penalties. And another creditor.”
“How much now?”
“Around fifty-two thousand.”
I wrote the figure down. She watched my pen move as though it might transform the number into a judgment.
“Grant said a home-equity arrangement could give us breathing room,” she continued. “Caroline could repay us when her business recovered.”
“And if it didn’t?”
“We would have had time to work that out.”
“You were planning to borrow against our house to pay another person’s creditors, and you wanted me to find out afterward?”
She started crying. “I thought you would understand when she was safe.”
“Safe from what? A collection call? Our house is the thing you offered.”
For the first time, she didn’t argue.
I asked how a discussion about fifty-two thousand dollars had led to a private appointment at a hotel. She told me Grant had no fixed office nearby, that he traveled between clients, and that the Hawthorne Grand had a quiet room where they could review documents without interruption.
“He said meetings at the hotel were normal for his work,” she murmured.
“And you believed him?”
“I wanted to.”
Those three words were the most truthful she’d sounded since the kiss at our front door.
She unlocked her phone and showed me a message thread. I didn’t take it from her. She scrolled while I read. There were ordinary greetings, reminders to send information, and repeated assurances that her husband could be brought in later. I asked her to forward the thread to an email address we could both access for records. She hesitated, then did it in front of me.
On the screen, one message stood out.
We can run the valuation before the second owner comes aboard. No need to alarm him about a preliminary review.
Grant had sent it three days before the hotel meeting.
“You knew I wasn’t being consulted,” I said.
“I knew he wanted to move quickly.”
“That’s another way of saying the same thing.”
Her shoulders sagged. The woman I’d known for eleven years had become a stranger through small choices, each one apparently easier than telling me the truth.
Then I saw a second message, sent from her phone.
He’ll say no if I bring it up now. I need to show him it’s already possible.
I looked at her. She stared at the countertop.
“You weren’t afraid I’d misunderstand,” I said. “You were afraid I’d disagree.”
She didn’t deny it.
We spent the next hour sorting the facts without giving Grant another warning. My wife opened the email account she had used for the application. She showed me the mortgage statement, the tax-return summary, and the house-value estimate she’d uploaded. There was also a scanned page from the closing packet we’d signed six years ago, the page bearing both our signatures.
“Why would he need that?” I asked.
“To confirm we owned the property.”
“A public record could confirm that. Why a page with our signatures?”
She whispered, “I didn’t think about it.”
I took a photograph of the document as displayed and wrote down the email’s date. I wasn’t certain the signature had been misused, but I finally understood how somebody could have obtained a model of mine without speaking to me.
The appraiser’s business card lay beside the hotel key. I called the number printed on it and asked for his supervisor. After verifying the assignment, she confirmed that the visit was suspended pending clarification of consent. She was careful about what she could disclose; the company was a subcontractor, not the lender, and she could not certify whether anyone had actually applied for credit in my name.
“Can you tell me which organization ordered the appraisal?” I asked.
She gave me the name of the coordinating firm listed on the work order and advised me to contact them directly. I wrote it down, thanked her, and ended the call.
My wife was searching the same name on her laptop. The result looked professional: a website with photographs of office buildings, a long explanation of secured financing, and a contact form. None of it told me whether Grant was an employee, an outside referral agent, or simply using a legitimate company’s name.
“He sent me that website,” she said.
“Sending a link isn’t proof he works there.”
I found a telephone number through the company’s public contact page and called it myself. I described a disputed residential appraisal and asked for the compliance department. The receptionist transferred me to someone who identified herself as a fraud-review specialist.
I explained only what I could substantiate: a visit had been requested in my name, I hadn’t approved it, and my personal financial documents had been supplied without my knowledge. She declined to discuss any application specifics until their identity-verification process was completed. She gave me instructions for submitting a written dispute and told me not to send sensitive records to an unverified email address.
It was the first sensible instruction I’d heard from anyone connected with the transaction.
“Is there a closing scheduled?” I asked.
“I can’t confirm that on this call,” she said. “What I can do is flag the reported impersonation for immediate review. Keep your reference number.”
She read it twice. I wrote it beneath the appraiser’s number.
My wife looked relieved when I hung up.
“So they’ll stop everything.”
“They’ll investigate,” I corrected. “We still don’t know what Grant submitted or whether this company is even the only one involved.”
That answer seemed to frighten her more than my anger.
I called my bank next, using the number printed on my debit card, and asked how to report possible misuse of my identity. They explained the difference between checking my existing accounts and protecting my credit elsewhere. I secured my online banking, reviewed recent activity, and began the process of placing freezes with the credit bureaus. Nothing on the screen proved a new loan had funded. At least I could stop pretending that meant nothing had happened.
Around noon, Caroline called my wife’s phone. My wife stared at the caller ID before answering on speaker at my request.
“Did you fix it?” Caroline asked immediately.
My wife closed her eyes. “Not yet. He’s here.”
A silence followed.
“I need to speak with both of you,” I said.
“I told her not to drag you into this,” Caroline replied.
“Then start with why you introduced her to Grant.”
Caroline sounded exhausted. She admitted she had found Grant through an acquaintance who claimed to specialize in emergency business financing. He had told Caroline that the business itself lacked sufficient collateral, but a relative who owned a house might qualify for another arrangement. Caroline insisted she hadn’t asked my wife to hide anything from me.
“Did you know she met him at a hotel?”
“No. I thought he was taking her application at an office.”
“Did you ever meet him?”
“Once. For coffee.”
My wife shook her head urgently, warning her sister not to say more. I caught the movement.
“What are you afraid she’ll tell me?” I asked.
Caroline exhaled. “He asked for a processing payment before he would show us a final proposal. I thought it was strange.”
“How much?”
“Forty-eight hundred dollars.”
My wife whispered, “It’s refundable.”
Caroline answered before I could. “That’s what he told you. I told you to stop when he asked for it.”
I looked at my wife. “You paid him?”
She nodded once.
It wasn’t proof of a crime, but it was proof of another omission. She had taken nearly five thousand dollars from savings she controlled and sent it to a recipient she couldn’t clearly identify. The payment hadn’t appeared in the household account I’d reviewed because it came from her separate savings account. She showed me the transfer confirmation voluntarily. I copied the date, amount, and recipient description into my notes.
“Why didn’t you tell me about the fee?” I asked.
“Because I was already too far into it.”
“That’s not a distance,” I said. “That’s a series of decisions.”
Caroline began to apologize. I stopped her.
“I need you to preserve every message you received from Grant. Don’t delete anything. But please don’t contact him until we have advice about what to do.”
She agreed. Before hanging up, she said something that made my wife look away.
“I never asked you to risk your marriage for my store.”
When the call ended, we sat in silence. Her sister’s trouble was real. So was the pressure she had felt to help. Neither fact explained why she’d used me as an obstacle to be bypassed instead of a partner to be consulted.
I found the number of a local attorney who handled real estate and consumer fraud matters. Her receptionist arranged a consultation that afternoon and instructed us to bring copies of whatever we actually possessed, not guesses about what might exist. I sent the dispute reference numbers, the appraisal details, and the message exports to a folder under my control.
Before leaving, I asked my wife one final question about Room 614.
“Was Grant alone?”
She hesitated. “Yes.”
“Did anything happen between you?”
“No. He spread paperwork across a desk and talked about the loan. He said he was helping me save my sister.”
I believed that might be true. The hotel room had always made me imagine a lover. It was somehow worse to picture my wife sitting beside a stranger, discussing what our house was worth while I assumed she was buying furniture with her sister.
“When did you realize he was using my name?” I asked.
“This morning. When the appraiser said it.”
I kept my eyes on hers. “And before that, when he said he could proceed without alarming me?”
She looked down.
We drove to the attorney’s office in separate cars. I wasn’t trying to punish her. I simply couldn’t bear the idea of being trapped beside her for twenty minutes while she searched for another explanation that ended with asking me to wait until tomorrow.
The attorney, a woman named Mara Ellis, listened without interrupting. She didn’t promise she could undo every risk with one telephone call. She explained that an appraisal order wasn’t a mortgage, that a disputed application didn’t automatically create a lien, and that any use of my identity without authorization needed to be documented carefully. She asked us to preserve records and not sign new documents simply because someone claimed a deadline was approaching.
Then she turned to my wife.
“Did Grant ever ask whether your husband would object?”
My wife’s face tightened.
“Yes.”
“What did you tell him?”
“That he would be upset if I brought it up before there was a solution.”
Mara waited. “Anything else?”
“I said he’d never agree to put the house at risk for Caroline.”
“And what did Grant say?”
My wife stared at the folder on the desk. “He said we could establish the value first and deal with signatures later.”
Mara asked her to show the messages again. My wife opened the thread. Mara read the lines slowly, making no judgment aloud. Then she pointed to an attachment sent the morning after the hotel meeting.
“Have you opened this?”
My wife nodded. “It was a preliminary application.”
“May I see it?”
She tapped the attachment and handed Mara the phone. The document contained our address, an estimated property value, a proposed credit amount far above Caroline’s fifty-two-thousand-dollar problem, and two fields identifying us as applicants. Beside my name appeared a small electronic signature image that looked disturbingly familiar.
I leaned forward.
“That’s not mine,” I said.
Mara raised a hand gently. “Don’t assume how it was placed there yet. We’ll ask for the signing record and dispute its authenticity.”
She showed us a line beneath the signature fields. It listed an email address I had never used.
“Who controls this address?” she asked my wife.
My wife whispered, “Grant set it up.”
“For your husband?”
“He said it was just for receiving the preliminary documents.”
Mara sat back. “Then we need to establish who accessed it. The lender will need to know that your husband never consented.”
My wife reached across the table, but I drew my hand away.
“You told me you didn’t sign my name,” I said.
“I didn’t. I swear.”
“But you knew he created an account in my name.”
“I thought it was temporary.”
“A temporary version of me?”
Her face crumpled. Mara let the silence remain long enough for the answer to become obvious.
Mara helped me prepare a written notice disputing any purported approval, electronic signature, or authority to use my name. She emphasized that the company would have to examine its records and that her office would seek the relevant documents through proper channels. Nothing was declared magically canceled while we sat there.
But something did change.
My wife could no longer make our problem disappear by asking me not to call someone. The evidence had been placed in front of a professional who wasn’t obligated to accept her explanations, and I had a record of what I’d actually said and done.
As we gathered our papers, Mara asked my wife to check whether Grant had sent any other attachment from Room 614.
My wife scrolled through the thread. A message from that night appeared beneath a photograph of the hotel desk. The message had been sent by her, not Grant.
I’ve attached the closing page with his signature. Please don’t contact him until the money is ready.
I stared at the words. She had told me the signature page was needed to verify ownership. Now I saw she’d supplied it with instructions to keep me out.
“Did you know what he might do with that page?” I asked.
She began shaking her head, then stopped.
“I knew he wanted it,” she admitted. “I didn’t ask why.”
Mara’s expression hardened. “We need copies of the original message and attachment.”
Then my wife’s phone rang. The name on the screen was Grant.
She looked at Mara, then at me.
“Don’t answer yet,” Mara said. “We’ll decide how to handle contact after preserving the record.”
The call ended. A message arrived immediately afterward.
Your husband has filed a dispute. You need to tell him about the second authorization before someone else does.
My wife read it once. Her hands went cold around the phone.
“What second authorization?” I asked.
She didn’t answer.
Mara leaned forward. “Show me exactly what he means.”
And my wife finally said the sentence she’d been avoiding since the night I found Room 614.
“There was another form,” she whispered. “And this time, I knew it was supposed to be signed in your name.”
✓ Lynn R. Adams
The appraiser stood on our porch holding a work order with my name on it. Behind me, my wife gripped the doorframe. She had sworn she hadn’t signed anything for me, yet somebody had apparently confirm…