“Cancel your wedding and give your sister the $65,000. She deserves her dream venue.” My father said that in front of nearly sixty guests at my engagement brunch, just three weeks before I was supposed to get married. When I refused, he slapped me across the face. My younger sister stood frozen, and everyone went silent. Then my fiancé returned, saw my cheek, and confronted Dad. What my father didn’t know was that Michael and I had discovered something about his house, something that made his threats about my inheritance far less frightening than he imagined.
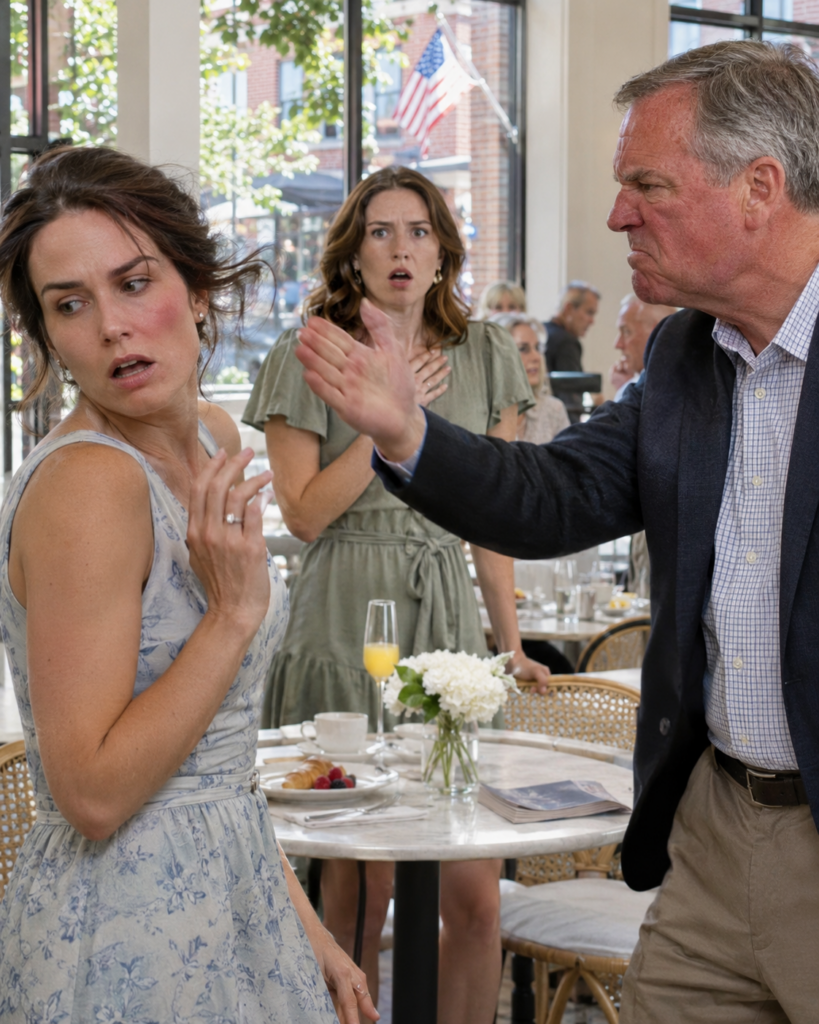
My Father Demanded $65,000 for My Sister’s Wedding. Then My Fiancé Mentioned His Mortgage.
My father had just threatened to cut me out of his will when my fiancé mentioned the one thing Dad never expected us to know about: the new mortgage application on his house.
We were standing in the middle of a café filled with almost sixty people, three weeks before my wedding. My left cheek was burning where my father had slapped me. A half-eaten piece of lemon cake sat on the table between us, beside a brochure for a wedding venue that cost more than most people in our family earned in a year.
“Richard,” Michael said, “your lender contacted Nancy twelve days ago.”
For the first time that morning, my father looked frightened.
He had been perfectly comfortable ordering me to cancel my wedding and hand my younger sister, Laura, $65,000 for the deposit on her dream venue. He’d been comfortable telling me I could earn it again. He’d even been comfortable hitting me when I said no, with family, friends, and the café staff watching. But the mention of that phone call made him look from Michael to me as if we had opened a door he thought was locked.
“That’s not your business,” he said.
“It became my business when you put my name on the application,” I answered.
Laura, who had been standing beside the table with the venue brochure in her hand, looked up. “What application?”
Dad’s jaw tightened. “Nancy is twisting something she doesn’t understand.”
“Then explain it,” Laura said.
Michael kept his phone at his side. He wasn’t recording a performance or threatening to expose Dad online. He had a copy of the message I had received from the lender, and he’d asked me with one look whether I wanted this discussed in front of everyone. I had nodded. By then the guests had already heard about the $206,000 I’d put into my parents’ house and the $12,600 college bill I’d quietly paid for Laura. I was finished keeping his accounts private while he treated my money as public property.
“The loan officer called to confirm two things,” I said. “That I was willing to sign onto your new refinance, and that I would release the mortgage securing the money you borrowed from me seven years ago without being repaid.”
Laura’s eyes moved to Dad. “You were going to borrow money for my wedding?”
“I was exploring options,” he said.
“And you told the bank I’d agreed,” I said. “I hadn’t.”
He reached for the back of a chair, then seemed to notice the people watching and straightened. “You have no idea how families are supposed to help each other.”
“I know exactly how I’ve been helping this family.”
The café manager came toward us, looking worried. He quietly offered to call someone or open the office so I could sit down. I thanked him and said I wanted a few minutes. There was a cup of coffee going cold on the table, and my mother was staring at it as though the pattern in the foam might tell her what to do.
It is strange what stays with you after a public humiliation. I remember the sound of a spoon dropping into a saucer. I remember Michael taking one step closer without putting his hands on me. Mostly I remember realizing that nobody in the room could make me go back to pretending my father hadn’t struck me.
Three weeks earlier, I would have done almost anything to keep the peace at a family gathering. That morning, I’d already paid too much for it.
My name is Nancy Collins. I’m thirty-three, and I work in operations for a regional medical supply company. I like spreadsheets, clear schedules, and knowing which bill is due on which date. Those habits aren’t glamorous, but they’ve kept me steady through job changes, two apartments, and years of being the person Dad called when his plans went wrong.
Michael, my fiancé, is a building systems engineer. He worries about a loose handrail the way I worry about an unexplained charge on a bank statement. We met five years ago through a mutual friend. After years of other people’s emergencies interrupting our plans, we were finally getting married in a small garden venue we’d reserved eighteen months earlier. The wedding was paid for except for final vendor balances. Most of the money in our high-yield savings account was intended for a down payment on a condo.
Dad knew that. Three nights before the brunch, he’d called to ask whether we still kept the savings in that account. I thought he was making conversation. I had learned to tell him less about our finances, but apparently not little enough.
Laura is four years younger than I am. She teaches art at an elementary school, and her fiancé, Ben, works for the county parks department. They are good people, and neither has a salary that could justify an extravagant wedding. I knew she’d fallen in love with a historic estate outside the city, with terraces, old trees, and a ballroom that looked beautiful in photographs. I did not know its contract required a $65,000 deposit by Monday. Dad had promised to pay it, she said, and he’d led her to believe I was happy to contribute.
No one had asked me. Not once.
When Dad first stood up at the brunch and announced that I should postpone my wedding so Laura could have hers, a few guests laughed, assuming he was making an ugly joke. Then he said, clearly enough for the back tables to hear, “Cancel your wedding and give your sister the $65,000. She deserves her dream venue.”
I told him no. I told him Michael and I had commitments and a home to save for. He said, “You can earn it again.” I said he had used that sentence far too many times. The slap came so quickly I didn’t understand what had happened until I felt my cheek. Michael was outside helping his aunt find the correct entrance. He came back to silence, saw my face, and asked Dad what he’d done.
Dad called it private family business. Michael looked around the café and answered, “You just made it a sixty-person matter.”
Laura had insisted she never asked him to hurt me or cancel my wedding. Then she’d said Dad had promised to cover the venue himself. Her surprise was real. I could see it when she learned what I’d paid for the house and, afterward, for the balance on her student account. When Dad threatened to remove me from the family property agreement and cut me out of his inheritance, I told him to do whatever he legally could. He mistook that for surrender.
Now, as he watched Michael put the phone away, Dad tried another approach. “This family has a house because I kept it together,” he said. “I am not going to be lectured about it by someone who hasn’t had children or carried a mortgage for thirty years.”
“The house is still standing because Nancy helped you,” Mom said quietly.
We all looked at her. My mother, Elaine, rarely contradicted Dad in company. She’d spent most of my life soothing awkward moments before anyone could name what was wrong with them. Her face had gone gray, but she kept her eyes on him.
“Not here, Elaine,” he said.
“You chose here.”
Laura laid the brochure on the table and slid it away from herself. “I’m calling the venue today,” she said. “I’m not signing the contract.”
“Don’t be dramatic,” Dad said. “We can still work this out.”
“No,” Laura answered. “I thought you were giving us a gift. I didn’t know you were handing me a bill with Nancy’s name on it.”
Ben, who had been standing behind her, put a hand on her shoulder. She didn’t lean into him. She kept looking at Dad, waiting for an explanation that wasn’t coming.
Michael touched my elbow and asked, “Are you ready?”
I was. The room had become unbearable, not because anyone was staring, but because I could feel my old instinct to apologize creeping back. I was about to say I was sorry the brunch had been ruined, sorry Laura was disappointed, sorry Mom was embarrassed. None of those things was mine to repair.
The manager brought me a small bag of ice wrapped in a clean towel. I accepted it. Michael settled the café’s remaining balance with the manager before Dad could turn the bill into another argument. We left through a side door, not to escape responsibility but because there was nothing left to settle in front of an audience.
In the car, Michael waited until I had fastened my seat belt. “Do you want to go home?”
“I don’t know.”
“We can drive for a while.”
He pulled into a quiet side street. I held the wrapped ice against my face. My phone began to buzz with messages from cousins and two of my mother’s friends. One said she was sorry. Another asked if I was all right. I turned the phone over.
“I meant what I said,” I told Michael. “About not giving him another dollar.”
“You knew everything before today. But hearing the amounts out loud made me feel sick.”
“You’ve been carrying them in separate boxes,” he said. “He kept asking you to open one box at a time.”
That was exactly how it had happened.
Seven years earlier, I was twenty-six and living in a one-bedroom apartment with a leaking kitchen faucet I kept meaning to replace. I had been working steadily since college, saving hard and building a career in logistics and operations. A small inheritance from my grandmother and stock I had earned at my first job made up part of my savings. I’d been proud of having enough to think about buying a place of my own.
Dad called on a Tuesday evening and asked me to come over. When I got there, the kitchen table was covered in envelopes. My mother had been crying. The house, a two-story brick colonial where Laura and I grew up, had been refinanced into a complicated arrangement after Dad’s consulting income dropped. A short-term loan was coming due, and missed payments had left them facing collection and the real possibility of foreclosure proceedings if they couldn’t bring the accounts current.
The figure Dad needed was $118,400. I remember it because he made it sound both precise and temporary. He said a large consulting contract would pay in three months. He said the bank had been unreasonable. He said he had always protected his daughters, and now he needed me to protect the roof over Mom’s head.
Laura was twenty-two and just starting her career. Dad made me promise not to tell her. “She needs a chance to get on her feet,” he said. “She shouldn’t have to worry about adult problems yet.”
I wanted that for her, too. I didn’t understand that he was establishing a rule under which I would always be old enough to pay and she would never be old enough to know.
My mother did one thing right in those first days. She insisted we write down what I was giving them. A local attorney prepared a promissory note for the $118,400, with repayment due if the house was sold or refinanced. My parents signed a mortgage against the house to secure that note, subject to the existing senior lender, and the attorney had it recorded. Dad complained that formal documents made us seem like strangers. Mom said strangers weren’t the only people who needed clear agreements.
I kept a copy in a folder and didn’t think about it often afterward. Dad would mention that the family house would someday be ours, as though an inheritance was a suitable substitute for repayment. When I asked about the consulting contract, he said his clients were taking longer than expected. My parents kept the house, and I told myself that was what mattered.
Then the smaller calls began. Seventeen thousand dollars in overdue property taxes. Eleven thousand for a roof repair after a storm. Later, $28,000 in payments related to their home-equity debt. There was a furnace replacement for $9,800, an insurance escrow shortage of $6,200, and another $16,000 in scattered payments Dad said were needed to keep the monthly bills from snowballing. Each request had its own urgency and its own promise that this would be the last one.
The payments to protect the house totaled $206,400. The original secured note covered only the first $118,400; the later advances were documented by transfers, messages, and the paper ledger I maintained. I had never been eager to become my parents’ creditor. I was simply afraid of what would happen if I stopped.
The $12,600 I paid toward Laura’s remaining college balance was separate. Dad said he wanted her to begin adulthood without that debt and claimed he’d cover it. When he was short, he asked me to make the payment for him, then told me not to embarrass Laura by mentioning it. She sent him a thank-you card. I saw it on the mantel one Christmas and said nothing.
The home-equity account was where I made the mistake that kept following me. Dad persuaded me to join a new line of credit as a co-borrower when the existing second loan needed to be restructured. He said it would be temporary, just until his next contract was renewed, and promised he’d refinance me out within a year. I read the documents and signed them. I knew I was accepting responsibility. What I failed to do was insist on proof that he had removed me afterward.
For a while, he told me the balance was nearly gone. He would say, “That’s all handled, sweetheart,” when I asked. I stopped asking because I wanted to believe him. It was easier than admitting a decision I’d made to help my parents could damage my own future.
Six months before the brunch, Michael and I applied for a condo mortgage. Our loan officer asked about a home-equity account tied to an address where I’d never lived as an adult. There was still a balance of more than $30,000 and a monthly payment on my credit report. Dad had drawn on the line again after I had helped pay it down. It was not closed, and I was still responsible for it.
Our condo plans went on hold. The problem wasn’t that the bank hated my family. It was that a debt I’d thought was temporary was still a real obligation, and the lender had to count it when assessing our finances. We could have looked for a smaller condo or waited, but Michael and I agreed that first we needed to understand exactly what I’d signed.
That was when we opened the old folder, requested account records, checked the county filing, and began matching Dad’s messages to my transfers. I had spent years thinking of those payments as separate rescues. Seeing them in order made the pattern impossible to miss. Michael didn’t tell me I was foolish. He asked why I’d been so determined to keep it from my sister.
“Because Dad said she’d think less of him,” I answered.
“And what happens when you need help?”
I didn’t have an answer. I had never asked Laura for help, and I’d rarely told her when I needed any.
We met with a lawyer named Caroline Price, who handled real estate and debt disputes. She looked through the recorded mortgage and the family agreement. The original note still mattered, she explained, but that didn’t make me the owner of my parents’ home. It meant I had a documented claim that would have to be addressed in a sale or a refinance, according to its terms and priority. The later transfers weren’t automatically secured just because I’d made them. If my parents disputed those, recovering them could require negotiation or a lawsuit, with no guarantee of collecting everything.
Caroline also confirmed the part I most wanted to wish away: my signature on the home-equity debt was valid. Dad’s promise to take me off it didn’t release me. The lender would have to approve a change or the debt would have to be paid off. I went home angry at Dad, then angry at myself, then so tired I sat at the kitchen table until Michael brought me dinner.
I didn’t confront Dad immediately. I wanted the documents and a plan first. When I asked him for an updated statement on the home-equity line, he called me distrustful. When I mentioned the recorded note, he laughed and said, “You really think I’d sell your childhood home and leave you out?” I told him that wasn’t the question. He hung up.
Twelve days before the brunch, a loan officer at a different bank called me. My father had started a cash-out refinance application. My name had been provided as a prospective co-borrower, and the preliminary file said I had agreed to release the security for my $118,400 loan without a payoff. The bank needed to verify those points before taking the application further.
I said I had agreed to neither. I asked the officer to note that I had not authorized anyone to use my information for a new credit application and that I would not sign a release for no payment. He confirmed the application couldn’t proceed with me in those roles without my participation. I asked for that confirmation in writing and received it two days later.
The proposed cash-out amount was enough to make me wonder why Dad needed so much. I didn’t yet know about Laura’s venue deposit. I thought he was trying to cover the same old expenses with another loan. I was angry, but I intended to talk to him privately after the brunch, once I had stopped hoping for a harmless explanation.
Now I knew what at least $65,000 of that money was meant to accomplish. When the refinance couldn’t move forward on his assumptions about me, Dad had simply tried to take the money from my savings instead.
Back in the car, Michael asked if I wanted him to call Caroline. I said yes, and then surprised myself by crying. The pain in my cheek was fading, but I could still hear the noise of the café going quiet. My father had always spoken as if he were the final authority on what a good daughter owed. I’d never seen him strike Laura. I’d never thought he’d strike me, either.
“I don’t want him at our wedding,” I said.
Michael didn’t answer at once. We had spent months choosing music and discussing where family members would sit. His parents had been looking forward to meeting several of my relatives, including Dad.
“You don’t have to decide every part of that today,” he said. “But you do get to decide.”
That mattered more than he knew.
At home, I took a photograph of my cheek while the mark was still visible. Two guests sent messages saying they’d witnessed the slap and would confirm what happened if I needed them to. The café manager checked in, too. I saved everything in a folder. I wasn’t making a plan to punish Dad. I wanted a record because I knew how easily my family could turn an ugly event into a story about everyone being upset and no one being responsible.
My mother called that evening. I let it ring twice before answering.
“How is your face?” she asked.
“Your father is terribly upset.”
She went quiet. I heard the dishwasher running behind her, the ordinary sound of a house I’d helped keep. Then she said, “He shouldn’t have done that.”
“No, he shouldn’t.”
“He said you were trying to humiliate him.”
“He hit me in front of everyone, Mom.”
She drew a breath. “I know. I saw it.”
For years I’d worked around my mother’s silences, treating them as evidence that she was helpless. Now I couldn’t ignore that she had known about the loans, the transfers, and the way Dad kept Laura in the dark. She had occasionally thanked me in private, but she’d never stood beside me when I asked for repayment.
“I can’t keep being the emergency fund for your marriage,” I told her. “I love you, but no more money. And I will not sign that refinance.”
“I didn’t know he’d given the bank your name again,” she said.
“You knew about the rest.”
The honesty stung more than an excuse would have. She asked if she could come over the next day. I told her I’d think about it. After we hung up, I sat with Michael on our couch and watched the evening news without taking in a word.
On Sunday morning, Laura called. I nearly let that ring out, too, but then I remembered her holding the brochure as if it belonged to somebody else.
“I canceled the appointment,” she said. “We never signed, so there’s no deposit to lose. I wanted you to know before Dad told you something different.”
I thanked her. She began to cry, then apologized for crying. She said she’d spent the night reading the venue’s contract and wondering how she’d become a person who expected a $65,000 deposit to appear because her father had promised it.
“You didn’t know,” I said.
“I could have asked more questions. Ben did. He said it was an insane amount of money. I kept telling him Dad wouldn’t offer unless he could afford it.”
“Dad is very good at sounding certain.”
“You must have thought I was spoiled.”
“I thought you were my sister. I didn’t know what he was telling you.”
There was a long pause. Then she asked me about the college balance. I told her when I’d paid it, and why Dad had wanted me to keep quiet. She said she’d framed the little graduation photograph of herself and Dad because he told her he’d taken care of the last bill. He’d made that payment part of the story of what a generous father he was.
“I’m sorry,” she said. “I thanked the wrong person.”
“You don’t owe me a thank-you card, Laura.”
“Maybe not. But I owe you the truth. I had no idea.”
She asked if she and Ben could come by later in the week. She wasn’t asking for money or trying to broker a quick reconciliation. She wanted to hear what had happened, and she wanted us to speak to each other without Dad interpreting every sentence.
For the first time in years, I felt as though I might get my sister back.
My mother came on Monday carrying a grocery bag of peaches and a battered folder. The peaches were an old habit. When Laura and I were children, Mom brought fruit whenever one of us was sick, even if we had a fever and wanted nothing but crackers. She set the bag on my counter and looked around our apartment as if she were visiting for the first time.
“You and Michael have made this place nice,” she said.
“We’ve been here four years.”
“I know. I should have visited more.”
She didn’t ask me to forgive Dad. Instead, she opened the folder. Inside were copies of tax notices, loan statements, and emails. She had found records of several payments Dad told me he’d made from his consulting income. The money had come from my account. Seeing my transfer confirmations beside his claims to other family members was humiliating in a different way from the slap. He had not merely accepted my help. He had used it to build a reputation for being able to help everyone else.
Mom said the consulting business had once done well. After the disastrous refinancing, however, Dad began taking contracts with long payment schedules and spending the expected income before the clients paid. When an invoice was delayed, he borrowed. When borrowing became expensive, he told himself a bigger contract would fix it. He could not bear the idea of friends knowing he was struggling, especially after he’d spent years advising other people about financial decisions.
“Why didn’t you stop him?” I asked.
She sat at the table. “Sometimes I tried. Sometimes I was relieved when you helped because it meant I didn’t have to make him face it. I told myself we were going to repay you when things improved.”
“Things didn’t improve.”
“And nobody thought to tell me?”
She rubbed the edge of the folder with her thumb. “I was ashamed.”
I wanted to comfort her. That was another familiar impulse, and I let it pass. I told her that shame had cost me years of savings and nearly cost Michael and me our chance to buy a home. She didn’t argue. She said she would give Caroline any records she needed and that she would no longer sign loan papers she hadn’t read. It was a small promise, but it was the first one Mom had made to me that didn’t require me to do anything in return.
Before she left, she looked at the faint mark still visible on my cheek. “I didn’t protect you Saturday.”
“I don’t expect you to trust me because I brought a folder.”
“Good,” I said, more sharply than I intended. Then I added, “But thank you for bringing it.”
That afternoon, Caroline reviewed the bank’s written confirmation of the refinance inquiry. She helped me send a direct notice stating that I had not agreed to a new borrowing arrangement or a free release of my recorded mortgage. The bank acknowledged it and said the pending proposal involving me would not proceed. I also checked my credit files and placed safeguards against new credit being opened in my name without proper verification.
None of that made the old home-equity debt disappear. Caroline was careful about the distinction. The recorded note Dad owed me, the additional money I had advanced, and the home-equity loan I had signed as a co-borrower were three different problems. A letter could document my position. It could not magically release me from a valid contract or make my parents solvent.
She proposed a meeting with my parents to discuss an actual repayment plan. If they sold the house, the outstanding mortgages and my recorded claim would have to be dealt with in the closing process. If they stayed, they needed a realistic way to remove my liability from the home-equity account and stop borrowing against my future. The later advances could be negotiated separately. I asked whether I should sue.
“That’s an option we can discuss if they refuse to deal with you,” she said. “But I want you to understand the cost, the time, and what you could realistically collect. A judgment isn’t the same thing as money in your bank account.”
It was disappointing advice, which made me trust it. Dad had spent years promising that one large payment would fix everything. Caroline showed me that a real solution would probably be slow and incomplete.
I had barely reached my car when Dad sent a message: “If you insist on making lawyers part of this family, don’t expect me to be at your wedding.”
I stared at the screen. I had not threatened to exclude him. He was offering his absence as punishment, as though my wedding would be worthless without his approval.
I wrote back: “I will not discuss money with you by phone. Please communicate with Caroline about the loans. I also need you to acknowledge that hitting me was wrong before we discuss whether you will attend the wedding.”
He answered with a single sentence: “After everything I’ve done for you.”
I put the phone in my bag and went home.
Over the next few days, the story spread through the family in the way family stories do. Details disappeared. Opinions arrived. An uncle told me Dad had been under tremendous pressure and deserved a little understanding. A cousin asked whether I had really told him he couldn’t walk me down the aisle. Someone else said the argument should never have happened in public. I wondered how they imagined I could have kept a slap private while it was happening in front of them.
Laura put an end to several of those conversations. She sent a calm message to our extended-family group: “I was there. Dad demanded that Nancy give me money for a venue she had never offered to pay for. He hit her when she refused. I don’t want anyone contacting her to defend that. Ben and I are choosing a wedding we can afford.”
She told me before sending it, and I said it was her decision. It was the first time she’d challenged Dad openly on my behalf. I didn’t need sixty people to take my side. I did need the people who had watched it happen to stop calling it a misunderstanding.
Laura and Ben came over Thursday with takeout from the little Thai place near our apartment. We ate around our crowded dining table while Michael showed Ben the cabinet hinge he’d finally fixed. The conversation was ordinary for a while. Laura talked about her students making clay bowls; Ben described a tree-planting project that had gone badly because a contractor delivered the wrong seedlings. It felt like having friends over, which was something Laura and I had almost forgotten how to do without Dad’s opinions filling the room.
After dinner, she asked whether I had ever resented her.
“Sometimes,” I admitted. “Not because you needed help. Because it seemed like you were allowed to have a life while I was responsible for keeping everybody else’s life together.”
She looked down. “Dad told me you loved handling money. He said it was your thing.”
“It is my thing at work. That doesn’t mean I enjoy paying other people’s bills.”
“I should have noticed you were always working,” she said. “Every time I invited you somewhere, you were picking up an extra assignment or trying to save for something.”
“You couldn’t see what I wasn’t telling you. But going forward, let’s ask each other directly.”
She nodded. We didn’t make a grand promise to be best friends again. She asked about the photographer for my wedding and offered to help with the family photographs, since Dad might not be there. Ben said they’d found a community garden with a small indoor hall for their own wedding the following spring. It wasn’t the estate, but they could pay for it themselves. Laura looked relieved when she said the price out loud.
Friday brought another surprise. Dad showed up at my office building shortly before five. The receptionist called to say a man claiming to be my father was waiting downstairs. I went to the lobby because I didn’t want him troubling the staff. Michael was on his way to pick me up, and I texted him where I would be.
Dad stood near the doors holding a manila envelope. He’d shaved and put on the blue jacket he wore to important meetings. There was no sign of the man who had lost control at the café, except that he wouldn’t look directly at my face.
“I thought we could speak like adults,” he said.
“You can make an appointment through Caroline.”
He held out the envelope. Inside was a draft release of the mortgage securing my original loan. He had highlighted a signature line in yellow. I looked at it, then at him.
“You still want me to sign this?”
“It’s just paperwork. The new lender won’t move forward while that old claim sits there. If we get the refinance done, I can put the household accounts in order.”
“The lender already knows I won’t release it for nothing.”
“Nancy, I’m asking you to help your mother keep her home.”
There it was, the same sentence in different clothes. He used Mom’s safety as the reason I couldn’t protect my own. I handed back the envelope.
“You can discuss paying off the note. I’m not giving away the only documented protection I have so you can take on more debt.”
His voice dropped. “Do you want us put out on the street?”
“No. I want you to stop making promises you can’t pay for.”
For a moment he seemed smaller, more tired. He said the business had been slow and that he couldn’t disappoint Laura after spending months telling her he’d give her a beautiful wedding. He was embarrassed that people at the brunch had heard the truth. That explanation made sense of his behavior without making it acceptable. He had been willing to risk my future to preserve a picture of himself as the father who could provide everything.
“Laura has already canceled the venue,” I said. “There is no $65,000 bill. You can stop now.”
He shook his head. “You think this is just about the venue?”
“No. I think you need me to keep rescuing you so you never have to say what you can afford.”
Michael appeared by the doors. Dad glanced at him, tucked the release back into its envelope, and left without saying goodbye. I stood in the lobby until his car pulled away. I had expected refusal to feel triumphant. It mostly felt sad. I’d seen my father frightened before, but he’d always managed to turn fear into an instruction for me. This time it remained his.
The following week, Mom asked us to meet at the house. Caroline advised me to keep money discussions documented, so I told Mom any agreement would have to be reviewed afterward. I agreed to come because I wanted to hear whether my parents were willing to make real changes. Laura and Ben came, too, at Mom’s request. Michael sat beside me at the familiar kitchen table, the same one that had been covered with bills seven years earlier.
Mom had made coffee but no dinner. For once, she wasn’t trying to turn a difficult conversation into a pleasant family visit. She had written down the monthly payments on the house, the home-equity account, property taxes, insurance, and what Dad’s business had actually brought in over the previous year. The totals weren’t hopeless, but they were not enough to support the house, more borrowing, and their ordinary expenses without assuming income that hadn’t arrived.
Dad called her figures pessimistic. He said two contracts were close to signing. Mom asked him to put signed contracts on the table. He couldn’t. She didn’t argue about whether the clients liked him or whether the market would improve. She asked what they planned to do next month if neither payment came.
“We have the house,” Dad said.
“We have payments on the house,” she answered.
Laura leaned forward. “Please don’t use my wedding as a reason to borrow more. Ben and I made our choice.”
Dad waved a hand. “You don’t understand what I’m trying to build for this family.”
“I understand that Nancy has paid for it,” Laura said.
His chair scraped the floor. I flinched before I could stop myself. He noticed. His eyes went to my face, and for a second he looked genuinely ashamed. He sat down again.
I took a sheet from my folder. It listed the transfers I’d made toward the house: $118,400, $17,000, $11,000, $28,000, $9,800, $6,200, and $16,000. At the bottom was the total, $206,400. The college payment was on a separate page because it had been for Laura, and I’d never intended to seek it from her.
“I did these things because I loved you,” I said. “But I can’t treat them as small favors anymore. I have a signed note for the first payment. I have records for the rest. I’m also still liable for a home-equity line you told me would be temporary. I need to be removed from that debt through a proper payoff or lender-approved refinance, and we need an honest plan for what you owe.”
Dad looked at the list for a long time. “You’re putting a price on raising you.”
“No. I’m putting a price on loans you asked for after I was grown.”
He started to argue, then stopped when Mom pushed a copy of his own signature across the table. She’d found the original family agreement among the papers. “We both promised to pay her,” she said. “We can disagree about how. We can’t pretend we didn’t.”
Dad turned to me. “If we sell, there’s nothing left for you and Laura to inherit.”
“Then we don’t inherit the house,” I said.
He looked startled by how little that frightened me. For years he’d treated the future ownership of the house as a reward he could grant or withhold, even while I was paying to keep it. But the house wasn’t a promise of safety anymore. It was an expensive property with debt, maintenance, and a complicated claim against it. I wanted my parents housed. I did not want to spend the rest of my life financing an idea of family pride.
Mom said she had already spoken with a real estate agent about a possible sale. Dad stared at her as though she’d betrayed him. She didn’t look away. She’d found smaller rentals near her sister, she said. There would be room for visitors, and less to maintain. If they sold at a reasonable price, they could pay off the bank loans, satisfy the recorded note, and discuss the remaining advances without asking me to finance another month.
“You’ve been talking about moving behind my back?” he asked.
“I’ve been looking at what we can actually afford,” she said. “You can help me do that, or we can keep pretending until someone else makes the decision for us.”
He stood and went into the backyard. No one chased him. We stayed at the table and drank cold coffee. It wasn’t the dramatic surrender I might have imagined years earlier. It was Mom opening a real estate listing on her phone and showing Laura the floor plan of a two-bedroom rental. It was Ben offering to help sort the garage. It was Michael asking me quietly whether I was ready to go home. Responsibility was being passed back to the people whose decisions had created the problem.
Before we left, Dad came in and said he’d think about the sale. Then he looked at me. “You’re really willing to let the house go?”
“I’m willing to stop paying to keep it,” I said. “That’s different.”
He didn’t apologize for the slap. I didn’t pretend the meeting had repaired what happened. But he’d heard the numbers in a room where nobody was asking me to make them disappear, and that was a beginning.
Our wedding was eleven days away. I had spent so much energy on my parents’ debts that I’d forgotten we still needed to choose the music for the procession. Michael found me one evening at the kitchen counter with two playlists open and our vendor schedule buried beneath bank correspondence.
“Can we have one hour without the house?” he asked.
We sat on the floor with takeout containers and listened to songs until we found one that made us both smile. Then he asked whether I’d decided about Dad. I told him I’d given Dad a clear condition: he would need to acknowledge what he’d done, agree not to discuss money at the wedding, and treat us respectfully. Dad had sent back a message about how fathers were supposed to walk their daughters down the aisle. He hadn’t mentioned hitting me.
“I don’t think he’s coming,” I said.
“Are you all right with that?”
“I’m sad about it. But I don’t want to stand at the ceremony wondering what he’ll do if he’s disappointed.”
Michael nodded. He didn’t tell me that everything happened for a reason or that I should forgive Dad before it was too late. He asked whether I wanted somebody to walk with me. I’d originally planned to walk alone, as I’d always said I wanted to. For the first time, that choice felt like a real choice rather than a way to avoid hurting anyone’s feelings.
“I’ll walk myself,” I said. “And meet you at the front.”
Laura helped me get ready on the morning of the wedding. Mom arrived with a small sewing kit, although my dress didn’t need fixing. The two of them worked out where to stand for photographs and how to keep the morning calm. When Mom saw me in my dress, her eyes filled with tears. She said I looked beautiful and then, almost as an afterthought, “I’m proud of how you handled everything.”
“I didn’t handle it perfectly.”
“You shouldn’t have had to.”
Outside, the garden was bright after an overnight rain. Our friends and relatives filled the rows of chairs. A few seats were empty, and I noticed them. My father wasn’t there. I knew people would ask questions later. But the day belonged to us, and I refused to spend it imagining explanations for his absence.
Michael stood at the front, straightening the cuffs of his jacket. When he saw me, he smiled in the familiar, slightly crooked way he did when he was trying not to show how nervous he was. I walked toward him to the music we’d chosen on our kitchen floor. Nothing spectacular happened. No one interrupted. We said our vows and exchanged rings, and the people who loved us stood up and applauded.
At the reception, Laura made a short toast. She spoke about how I’d taught her to ride a bicycle and used to wait at the end of the driveway until she could reach me without falling. She didn’t turn our family troubles into a public lesson. She simply said she was glad she could now be the person who waited for me sometimes. It was enough.
Late that evening, after the guests had gone, Michael and I sat in our hotel room eating two slices of wedding cake wrapped by the caterer. My feet hurt. His tie was hanging over a chair. We were married, and no one had needed to surrender $65,000 to make the day happen.
The changes at my parents’ house took months, not days. Dad resisted the idea of selling for weeks. He asked Mom to wait for one more contract, then another. She insisted they meet with a housing counselor and review the numbers with a real estate agent. Eventually the carrying costs and the absence of new income persuaded him to list the house. I did not arrange the sale, pay for repairs, or manage the move. That was difficult at first. I kept thinking of things I could do faster. Then I reminded myself that doing them faster was not the same as doing them for the right people.
The house sold five months after our wedding. The price was respectable but not the fantasy amount Dad had used for years when he talked about our inheritance. At closing, the senior mortgage and the home-equity line were paid off. My recorded $118,400 note was satisfied from the proceeds, and I signed the release only as part of that documented payoff. Caroline reviewed the paperwork. Weeks later, I checked that the old home-equity account showed a zero balance and was closed. For the first time since I’d signed it, I was free of a debt on a house that wasn’t mine.
The other advances were harder. My parents could not repay every dollar without leaving themselves unable to rent a place and live. With advice from separate counsel, we agreed on an additional payment from the sale proceeds and a written schedule for part of the balance. I understood I might never recover all of it. That wasn’t a happy ending to the money story, but it was an honest one. No more hidden transfers. No more promises tied to contracts that didn’t exist. And no more suggestion that my future inheritance should make me grateful for being owed money today.
Mom and Dad moved into a smaller rental twenty minutes from Laura. Dad took on a steadier position doing project estimates for a local contractor. I heard from Mom that he found it humbling to work for someone else after years of running his own business. I was glad he had the income, but I didn’t confuse employment with accountability. He and I still spoke rarely. Our conversations were brief, and we didn’t pretend the slap had been erased by the sale.
One afternoon, a letter arrived from him. It was handwritten, which was unusual. He said he had been wrong to hit me. He said he’d felt ashamed of the financial situation and had turned that shame into anger at me. He didn’t ask me to tell the family he was a good father. He didn’t demand a reply. I read the letter twice, put it in my desk, and wrote back a week later that I appreciated the acknowledgment. I was not ready to resume our old relationship. I didn’t know whether I ever would.
Laura and Ben chose a spring wedding at the community garden they’d found. They paid the deposit themselves, and Laura called to tell me the amount without hesitation. She asked whether I would help her make place cards. I said yes. It was a pleasure to help with something that cost an afternoon and came with no secret invoice.
Michael and I began looking for a condo again after the home-equity account closed. This time, when the loan officer went through my obligations, there was no payment on my parents’ house to explain. We chose a modest two-bedroom place with an aging maple outside the living-room window and a kitchen smaller than the one in my childhood home. It had enough space for us, a spare bed for guests, and a door that closed without sticking. We made an offer we could afford and waited through the ordinary nerve-racking weeks of inspection and paperwork.
On moving day, Laura brought sandwiches, Mom brought a box of dishes she’d kept for me, and Michael carried in the last lamp. I looked at the two keys the agent had handed us and thought about how many years I’d spent feeling responsible for a house where my name was mostly useful when a payment came due.
I wrote our names on the blank card beside the condo’s front-door buzzer. Then I pressed it into place, stepped inside, and turned the key.
✓ Lynn R. Adams
My Father Demanded $65,000 for My Sister’s Wedding. Then My Fiancé Mentioned His Mortgage. My father had just threatened to cut me out of his will when my fiancé mentioned the one thing Dad never exp…